This content explains Section 1231 of the Internal Revenue Code, which provides a special tax classification for certain business assets, treating gains as long-term capital gains and losses as ordinary losses. It details the core requirements, including business use and holding periods, and covers various asset types
In the complex world of tax accounting, not all gains and losses are created equal. When a business sells an asset, the tax consequences depend heavily on how that asset was used and how long it was held. Section 1231 of the Internal Revenue Code provides a unique "middle ground" classification for certain business assets. It offers a significant advantage to taxpayers: while these assets are used in a trade or business, the resulting gains are often treated as long-term capital gains, while the losses are treated as ordinary losses.
This distinction is vital because ordinary losses can be used to offset ordinary income without the same limitations that apply to capital losses, whereas capital gains enjoy preferential tax rates.
The Core Requirements of Section 1231
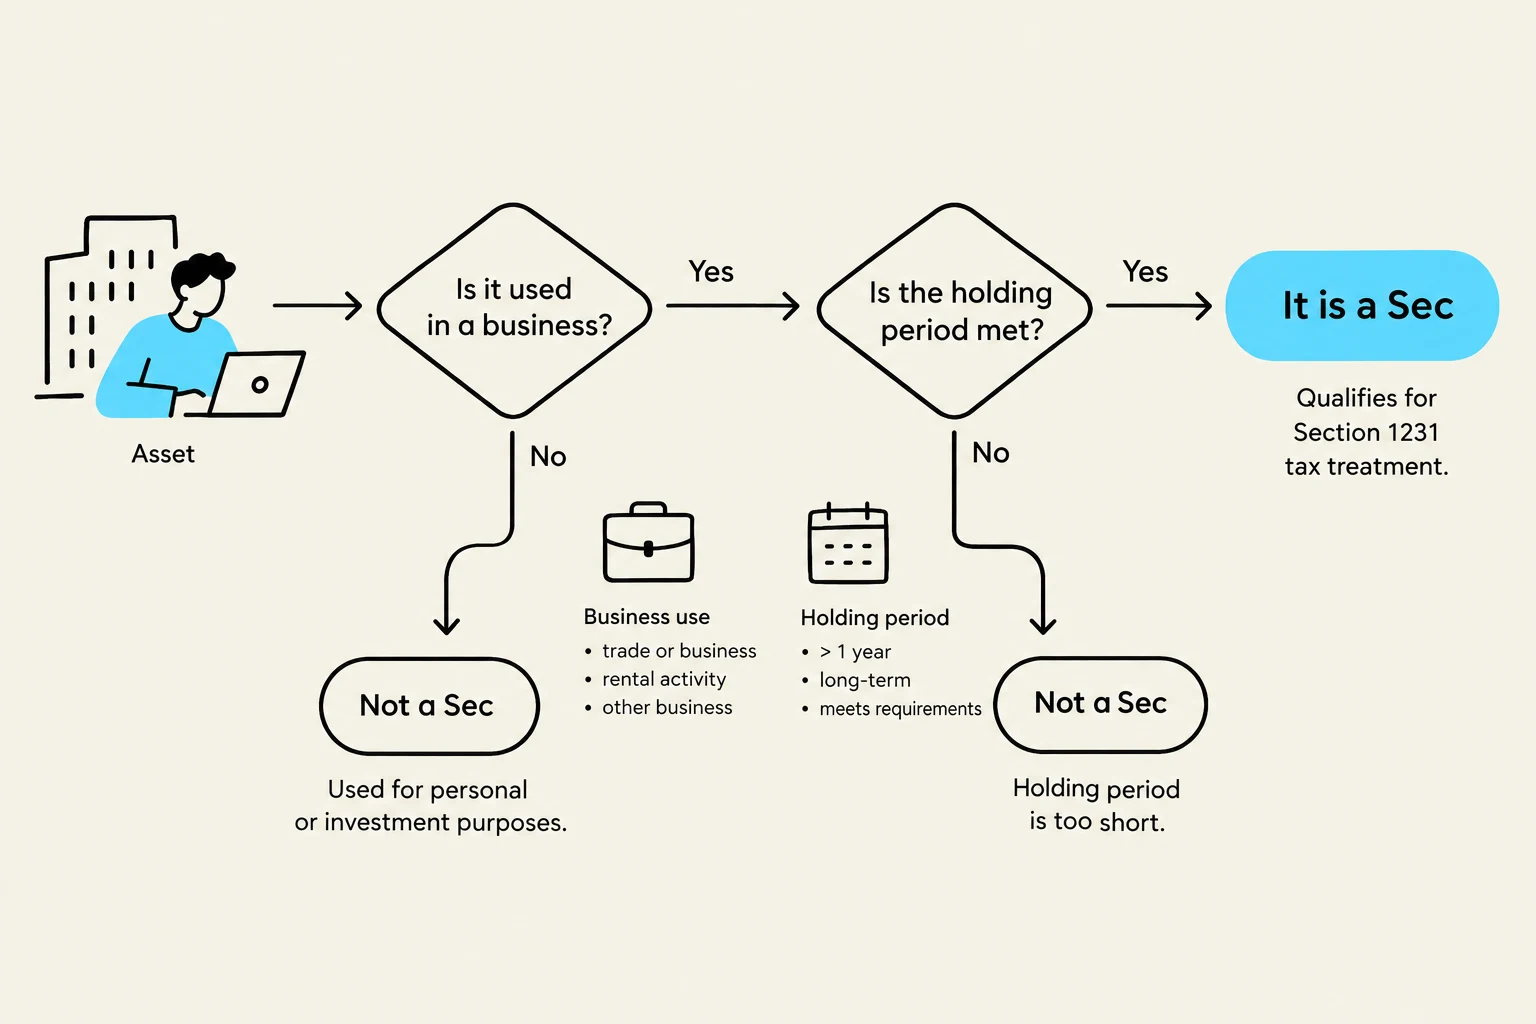
To qualify for Section 1231 treatment, a transaction must generally meet two primary criteria: the asset must be used in a trade or business, and it must meet specific holding period requirements.
It is important to note that "use in a trade or business" includes property held for the production of rents or royalties. If an asset is held for personal use, it cannot qualify for Section 1231 treatment, regardless of how long it is held.
Exam Tip: Always check the "use" and the "duration" first. If an asset is used for personal purposes (like your personal car) or held for less than the required period, it fails the Section 1231 test immediately.
Flowchart illustrating the criteria for an asset to be classified as a Section 1231 asset for tax purposes, considering business use and holding period.
Real and Depreciable Personal Property
One of the most common categories under Section 1231 involves real property and depreciable personal property.
Real Property and Depreciable Assets
Real property (such as land or buildings) used in a business must be held for longer than one year to qualify. Similarly, depreciable personal property must also be held for more than one year.
Depreciation and Intangibles
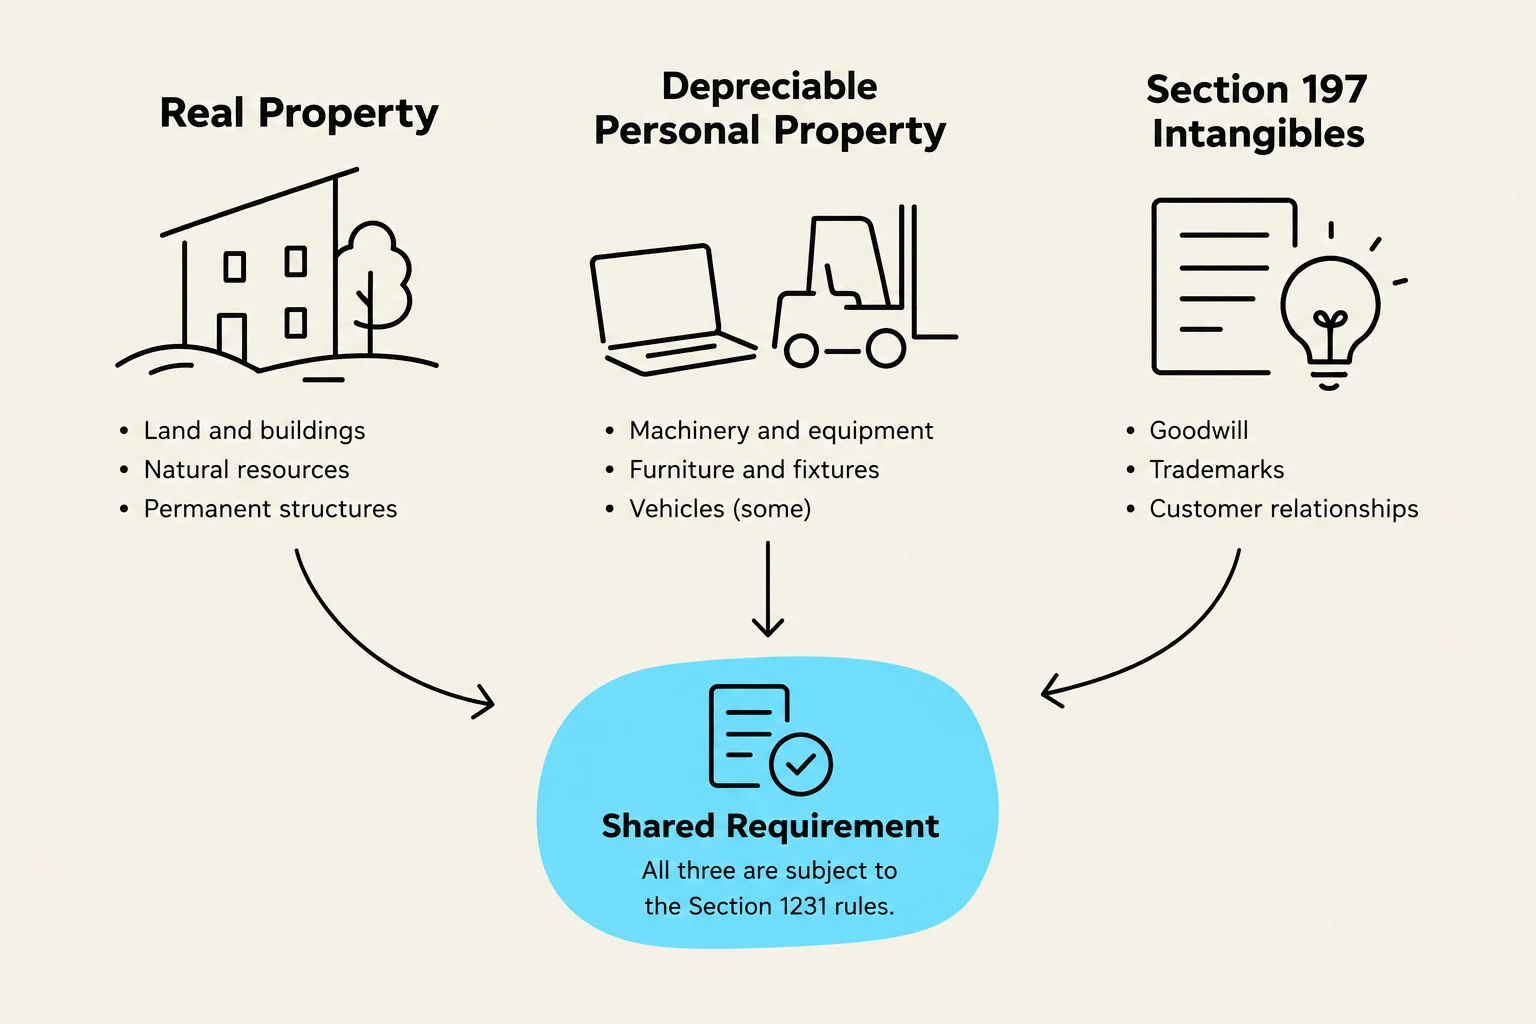
The law specifically references assets subject to depreciation under Section 167 of the Internal Revenue Code. This category is broad and includes:
Section 167 Depreciation: Physical assets like machinery, equipment, and vehicles that lose value over time through wear and tear.
Section 197 Intangibles: This includes certain amortizable intangible assets, such as goodwill or certain licenses, which are treated as depreciable personal property for Section 1231 purposes.
This diagram illustrates three categories of property: Real Property, Depreciable Personal Property, and Section 197 Intangibles, all of which are subject to Section 1231 rules.
Leaseholds and Specialized Assets
Leaseholds
A leasehold interest—the right to use a piece of property under a lease—can also qualify for Section 1231 treatment. However, the leasehold must be used in a trade or business and must be held for a duration exceeding one year.
Livestock
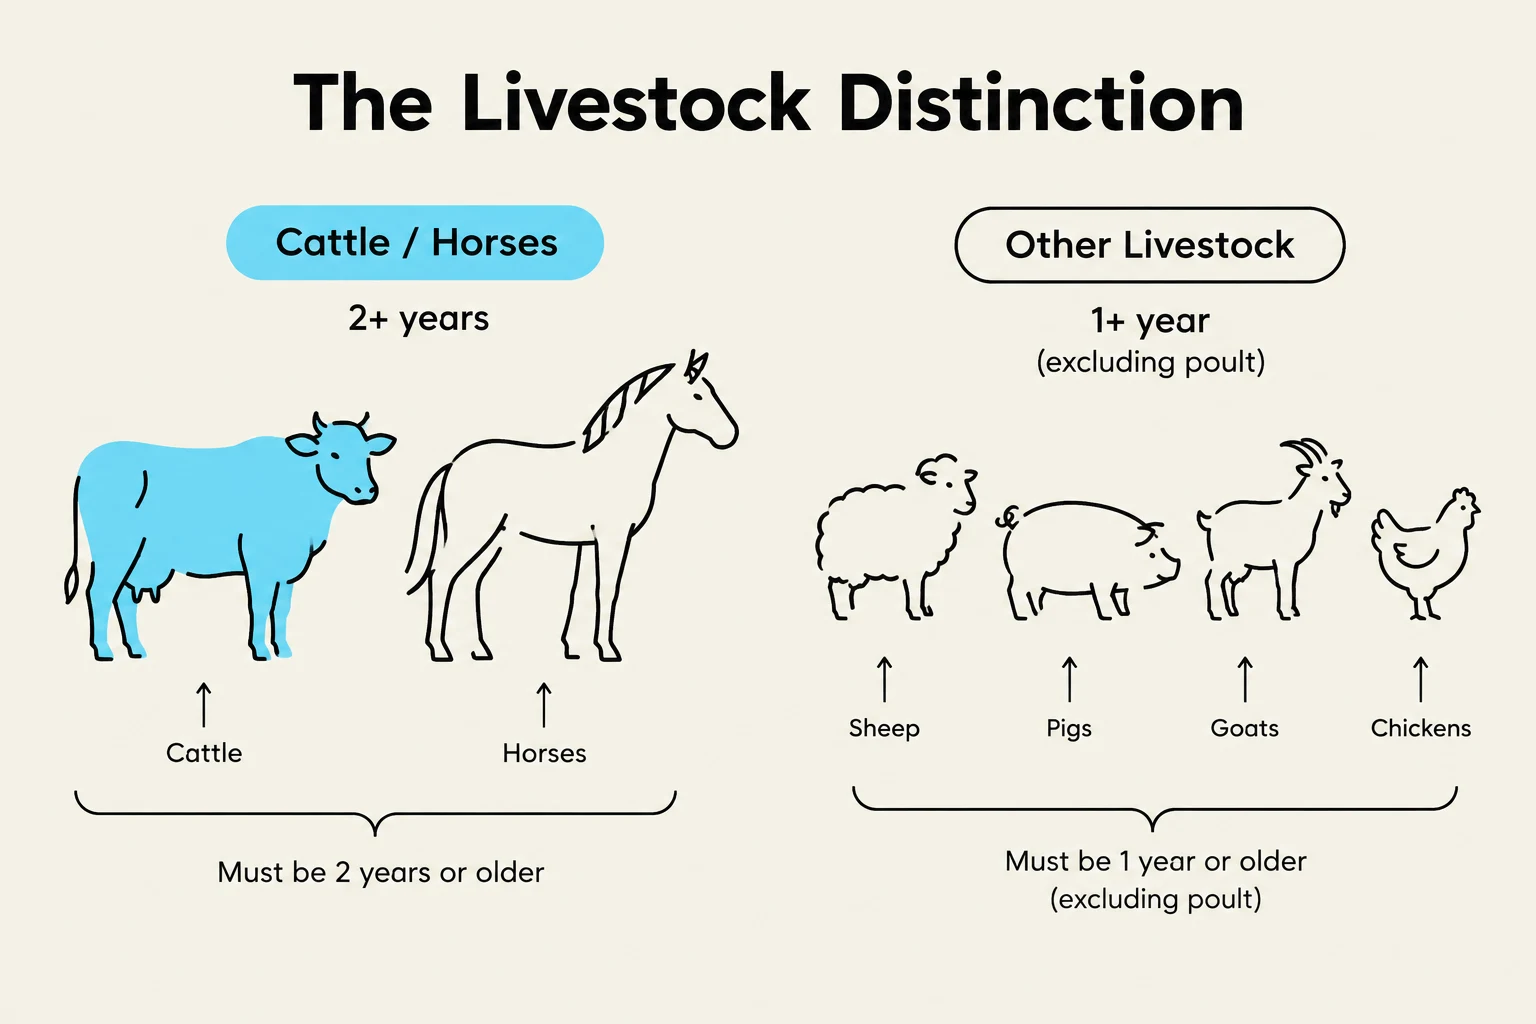
The tax treatment of livestock is more nuanced, as the law distinguishes between different types of animals and their intended purposes:
Cattle and Horses: These must be held for draft, breeding, dairy, or sporting purposes and must be held for two years or longer.
Other Livestock: This category includes various animals but specifically excludes poultry. To qualify, these must be held for draft, breeding, dairy, or sporting purposes and must be held for one year or longer.
This diagram illustrates the age distinctions for different types of livestock. Cattle and horses must be at least 2 years old, while other livestock like sheep, pigs, goats, and chickens must be at least 1 year old (excluding poults).
Unharvested Crops
A unique scenario occurs with the sale of unharvested crops. For these to fall under Section 1231 treatment, a specific "simultaneous" rule must be met:
The crop and the land must be sold, exchanged, or involuntarily converted at the same time.
The transaction must be made to the same person.
If a farmer sells the land in one transaction and the standing crops in a separate transaction to a different buyer, the Section 1231 treatment for the crops may be disqualified.
Summary Table of Section 1231 Assets
To help visualize the different requirements, refer to the following summary:
Asset Type
Business Use Required?
Holding Period Requirement
Real Property
Yes (incl. Rent/Royalty)
> 1 Year
Depreciable Personal Property
Yes
> 1 Year
Section 197 Intangibles
Yes
> 1 Year
Leaseholds
Yes
> 1 Year
Cattle and Horses
Yes (Draft, Breeding, etc.)
≥ 2 Years
Other Livestock (excl. poultry)
Yes (Draft, Breeding, etc.)
≥ 1 Year
Unharvested Crops
Yes (Land + Crop sold together)
Varies (Land must meet period)
Worked Example:
A construction company sells a heavy excavator used in their business operations. They purchased the excavator 18 months ago. Because the excavator is depreciable personal property used in a trade or business and was held for more than one year, the resulting gain or loss will be treated under Section 1231.
Keep reading for free.
Create an account to finish this reading and make it part of your study routine.