


In the complex landscape of tax law, Section 1231 serves as a critical bridge between two major categories of assets: ordinary assets and capital assets. For taxpayers, understanding Section 1231 is essential because it often allows for more favorable tax treatment on gains from certain business and investment properties. This article explores the specific requirements, categories, and exclusions that define Section 1231 property.
The Fundamentals of Section 1231
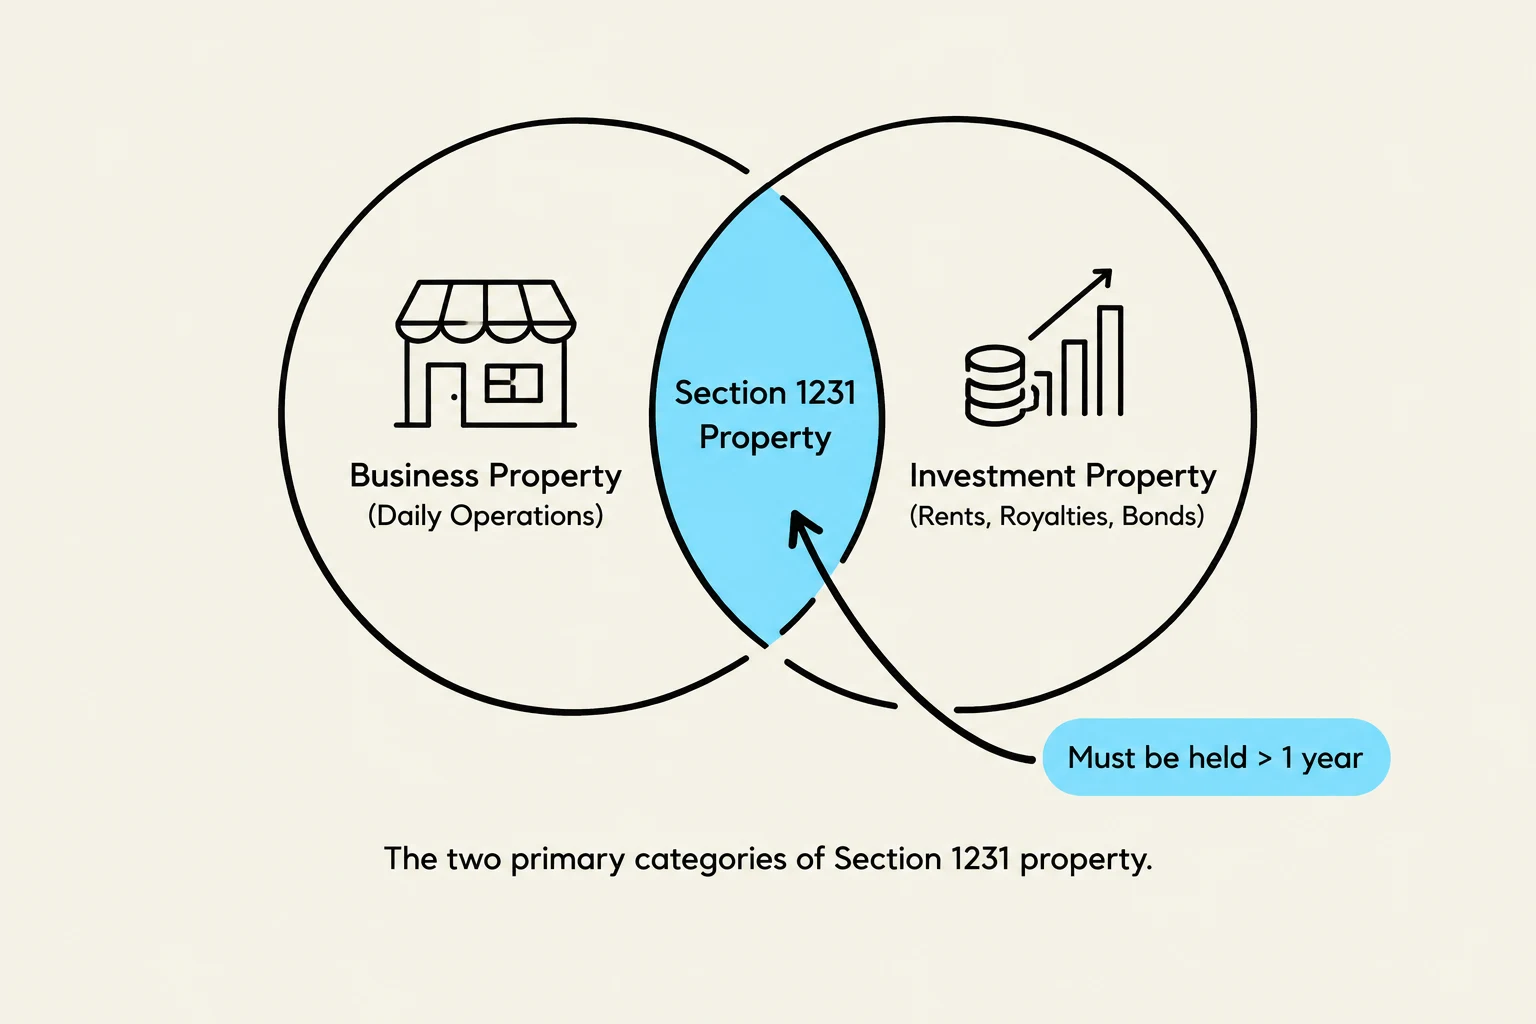
To qualify as Section 1231 property, an asset must meet two primary criteria: it must be held for more than one year, and it must be used in a trade or business or held for the production of income. This category typically encompasses two main types of assets:
- Business Property: Assets used in the daily operations of a trade or business.
- Investment Property: Assets held for the production of income, such as property held for rents and royalties, or financial instruments like notes and bonds.
Real Estate and Land Transactions
When dealing with land, the "more than one year" rule is strictly applied. Furthermore, a taxpayer cannot retain any right or option to reacquire the land, though exceptions are made for rights that are customary to a mortgage or other security transaction.
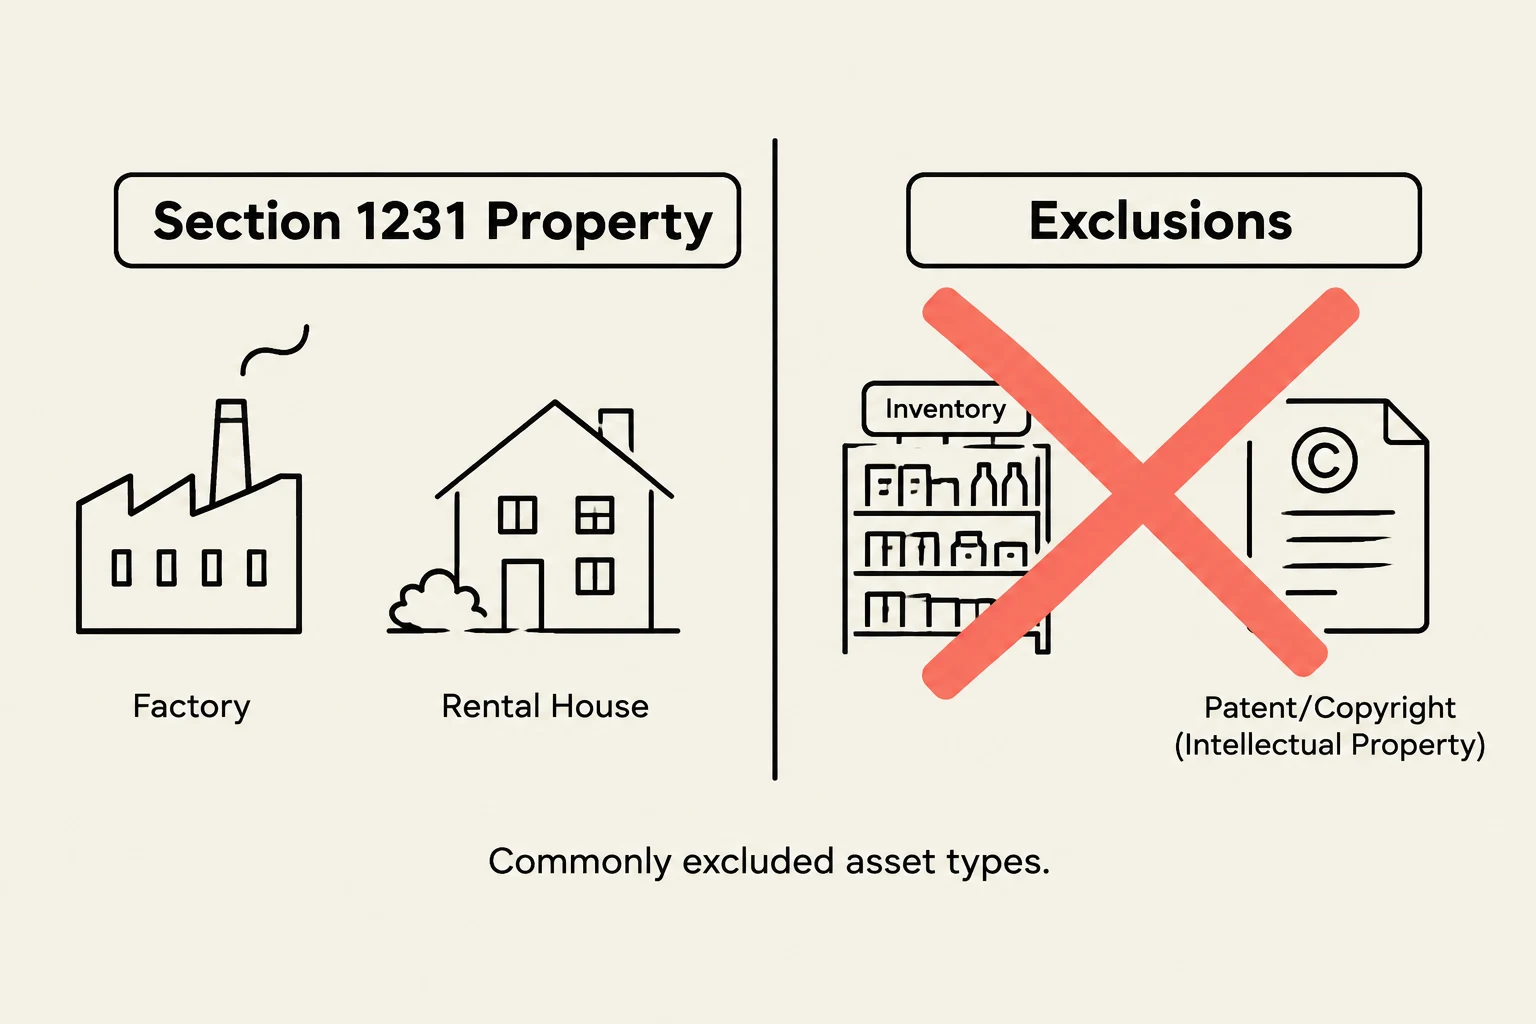
One nuance to watch for in exams involves the sale of crops. If a taxpayer sells growing crops alongside a land lease, those crops are excluded from Section 1231 classification, even if they are sold to the same person in the same transaction.
Keep reading for free.
Create an account to finish this reading and make it part of your study routine.
Continue reading freeAlready have an account? Log in
Updated