Understanding Mortgage and Notarial Bonds in Secured Transactions
This guide explains the fundamental differences between mortgage bonds and notarial bonds, their essential components, and various specialized types used in secured transactions. It covers how these bonds secure debts against immovable and movable property, respectively, and discusses legal exceptions and consumer prot
In the realm of secured transactions, creditors require robust mechanisms to ensure that debts are repaid. The law provides two primary vehicles for this purpose: mortgage bonds and notarial bonds. While both serve to secure obligations, they are distinguished by the nature of the property they hypothecate—immovable versus movable—and the legal rights they confer upon the creditor. Understanding these distinctions, along with the specialized variations of these bonds, is essential for navigating property law and credit security.
Mortgage Bonds: Securing Immovable Property
A mortgage bond is a limited real right over immovable property used to secure the repayment of a debt. Immovable property includes land and everything permanently attached to it, such as buildings and growing crops. It also encompasses certain real rights in land, such as registered long-term leases or usufructs.
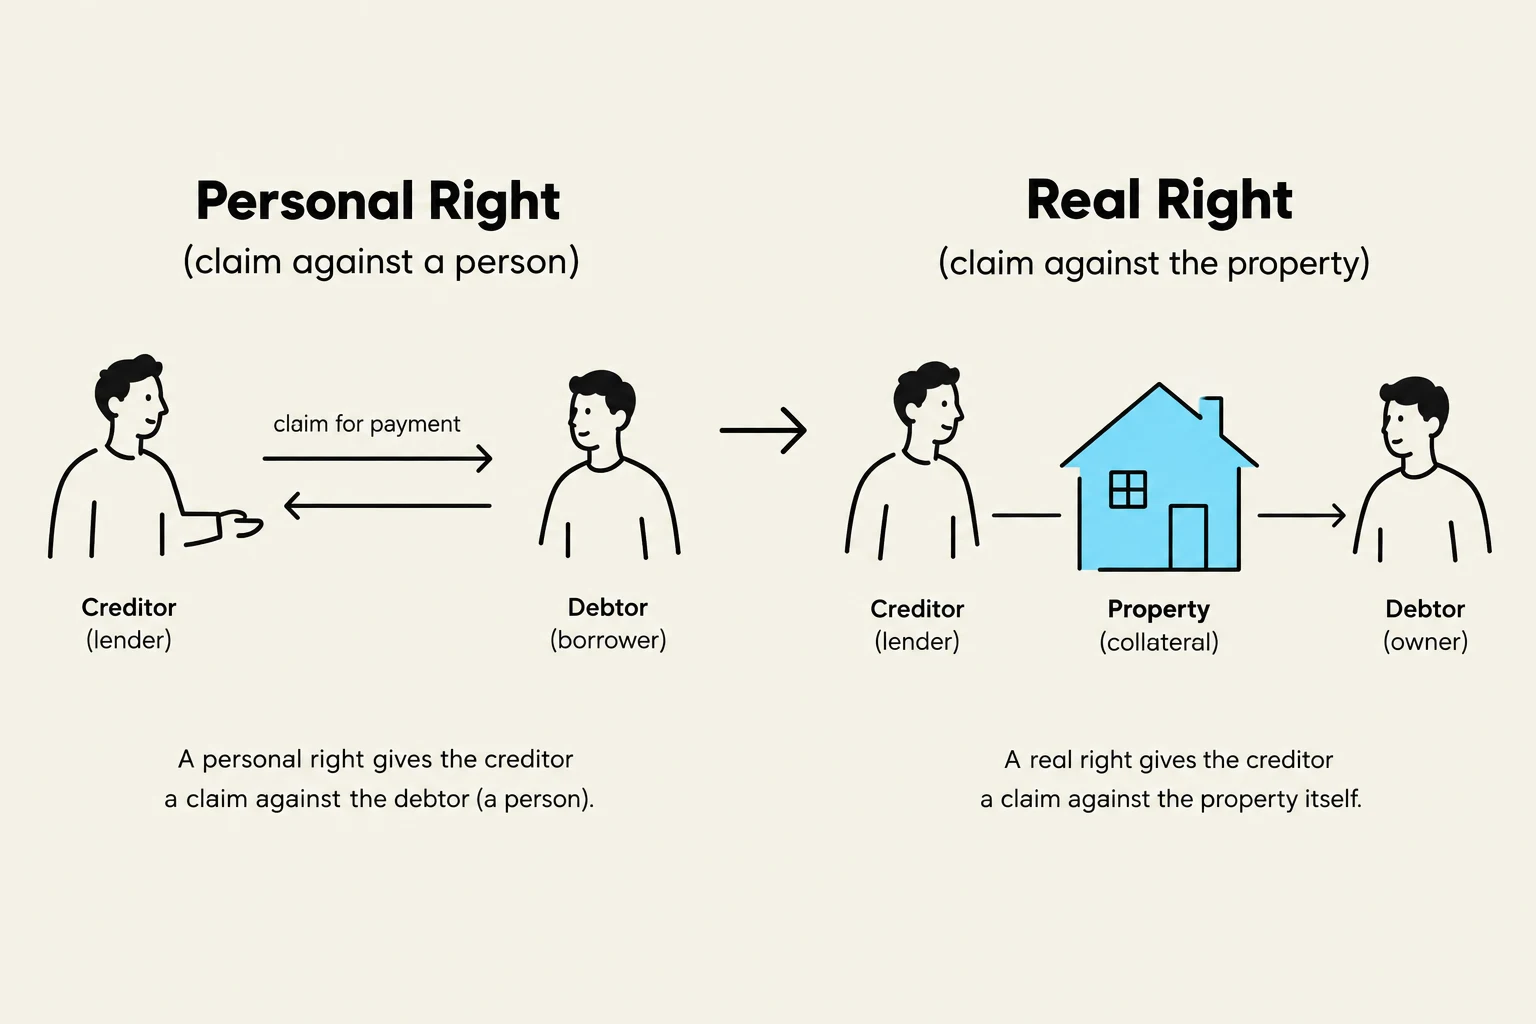
The critical distinction in mortgage bonds is the conversion of a personal right into a real right. Before a bond is registered, a creditor merely holds a personal right against the debtor—a claim that can be difficult to enforce against third parties. However, once the bond is attested by the registrar of deeds, the creditor acquires a real right. This provides two major advantages:
Preference: In a "concourse of creditors" (a situation where multiple creditors claim against a debtor's assets), the mortgagee has a preferential claim to the proceeds of the bonded property.
Control: The bond prevents the debtor from alienating (selling or transferring) the property without addressing the security interest.
This illustration differentiates between a personal right, where a creditor has a claim against a debtor (person), and a real right, where a creditor has a claim against a property (collateral).
Essential Components and Clauses
For a mortgage bond to be valid, it must contain several key elements:
Causa: The legal reason for the debt (e.g., a loan or the balance of a purchase price). Because a bond is an accessory right, if the underlying debt is invalid, the bond is also invalid.
Property Clause: A specific description of the immovable property being bound as security.
Amount: The maximum sum secured.
Execution Clause: A clause recording that the bond was signed and attested by the registrar.
Exam Tip: Remember that a bond is an accessory right. If the causa (the underlying debt) is non-existent or unlawful, the bond cannot legally exist.
Renunciation of Legal Exceptions
In many commercial bonds, the mortgagor is required to renounce certain common-law legal defenses, known as "exceptions." These include:
Non numeratae pecuniae: The defense that the money was never actually paid to the debtor.
Non causa debiti: The defense that there is no valid legal reason for the debt.
Errori calculi: The right to challenge errors in the calculation of the debt or demand a revision of accounts.
Important Note on Consumer Protection: Under the National Credit Act (NCA), consumers are protected from waiving these three specific rights. If a credit agreement contains a waiver of non numeratae pecuniae, non causa debiti, or errori calculi, that specific clause is void and will be severed from the agreement.
Notarial Bonds: Securing Movable Property
While mortgage bonds are reserved for land and buildings, notarial bonds are used to hypothecate movable property. This includes items such as furniture, business equipment, livestock, or even incorporeal assets like shares and liquor licenses.
Notarial bonds are attested by a notary public rather than the registrar of deeds. There are two primary types:
General Notarial Bond: Covers all of a debtor's movable property in general.
Special Notarial Bond: Covers specific, clearly described movables.
Under the Security by Means of Movable Property Act 57 of 1993, if the corporeal movables in a special notarial bond are described so clearly that they are readily recognizable, they are deemed "pledged". This grants the bondholder real security, providing preference even in the event of the debtor's insolvency.
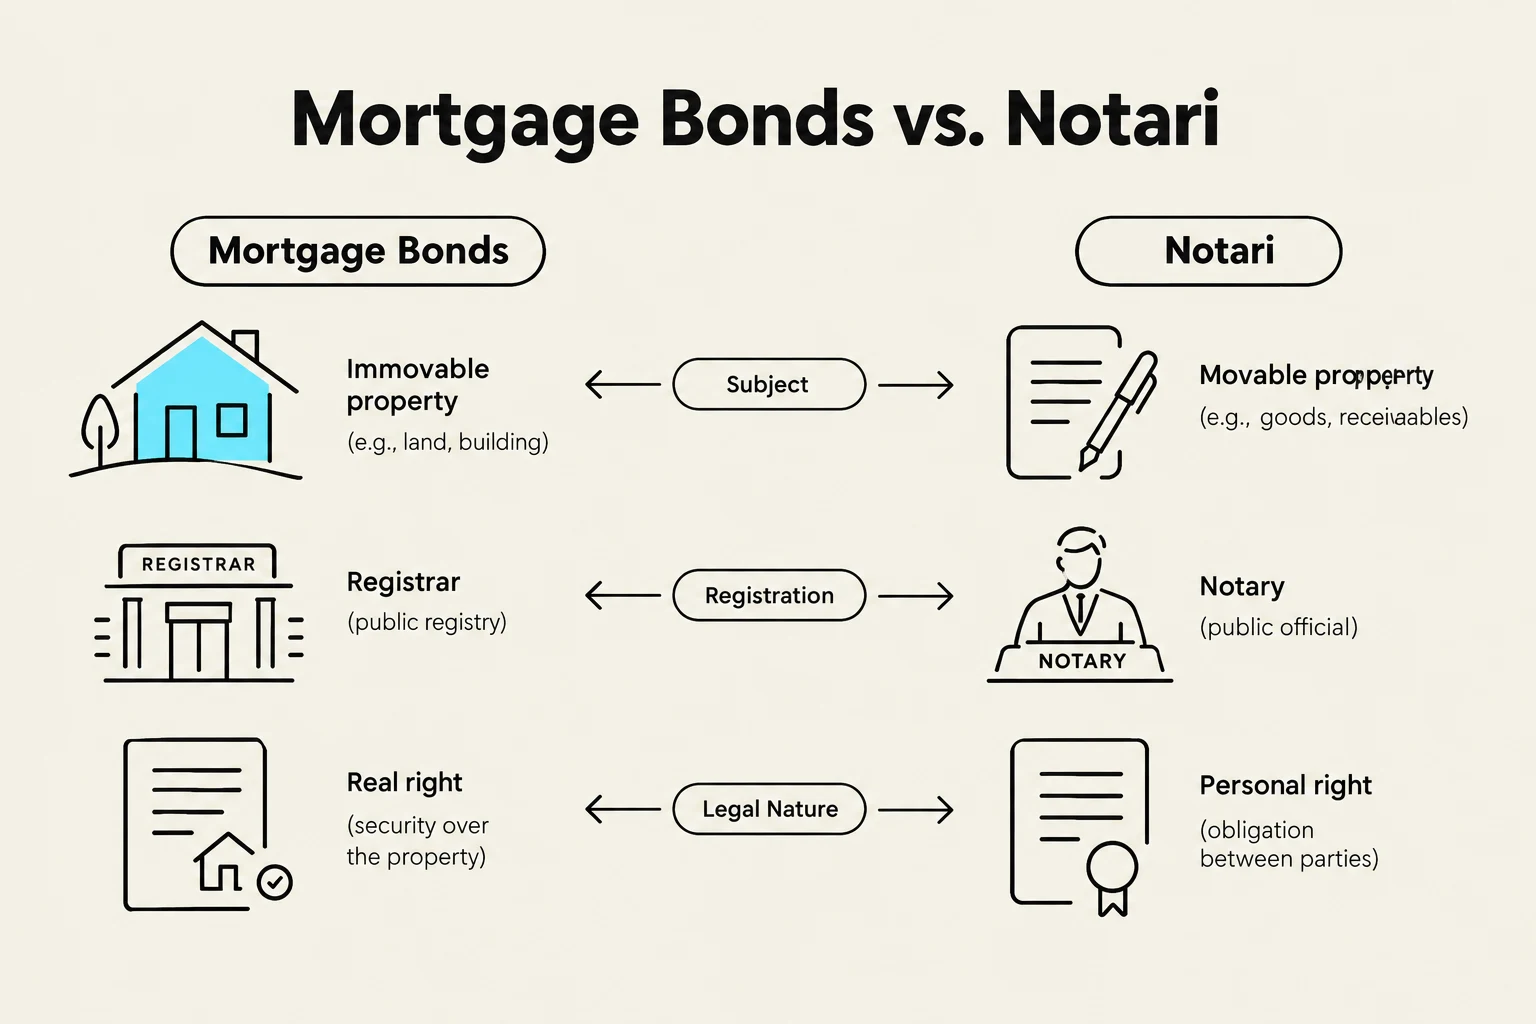
This diagram illustrates the distinctions between Mortgage Bonds and Notaries, covering aspects like property type, registration, and legal nature.
Specialized Bond Types
Beyond standard mortgage and notarial bonds, the law recognizes several specialized instruments designed for specific financial scenarios:
Security for Existing or Third-Party Debts
Collateral Bond: This is a bond passed by the same debtor to the same creditor for the same debt to provide additional security. For example, if a bank has a mortgage over a house, they might take a collateral bond over a farm to secure the same loan.
Surety Bond: A bond passed by a third party (the surety) to secure the debt of a principal debtor. If the debtor defaults, the creditor can claim against the surety's property.
Indemnity Bond: This is passed by the principal debtor in favor of a surety. It ensures that if the surety is forced to pay the creditor, the surety has a secured claim against the debtor's property to recover those funds.
Future and Specialized Obligations
Covering Bond: A bond designed to secure future or fluctuating debts, such as a bank overdraft. To be valid, it must expressly state it secures future debt and stipulate a maximum amount.
Kinderbewys Mortgage Bond: A specialized bond used to secure a minor's inheritance from a predeceased parent's estate. It is passed in favor of the Master of the High Court to protect the child's interests.
Kustingsbrief: An older term for a special mortgage registered simultaneously with a deed of transfer to secure the balance of a purchase price.
Participation Bond: A bond held by a nominee company on behalf of various investors, commonly used in collective investment schemes.
Debenture Bond: A specialized type of bond recognized in legal guidelines for securing corporate obligations.
Legal Benefits in Surety Bonds
When a third party acts as a surety, they may traditionally claim certain benefits to limit their liability:
Beneficium divisionis: The "benefit of division," allowing multiple sureties to insist that the claim be divided among them.
Beneficium ordinis seu excussionis: The "benefit of order or excussion," which allows a surety to demand that the creditor first exhaust all legal remedies against the principal debtor before coming to the surety.
In most commercial surety bonds, these benefits are expressly renounced so that the creditor can claim the full amount from any one surety immediately.
Keep reading for free.
Create an account to finish this reading and make it part of your study routine.