An overview of the four main market structures: perfect competition, monopolistic competition, oligopoly, and monopoly. This guide explains their key characteristics, including the number of firms, product type, price control, and barriers to entry, with examples for each.
In economics, a market structure refers to the organizational and competitive characteristics of a market. These characteristics determine how companies behave, how prices are set, and how much power a single firm holds over its customers. By analyzing these structures, we can predict whether a market will favor the consumer through low prices and high variety, or favor the producer through high prices and limited choice.
Understanding these structures is essential for grasping how resources are allocated in an economy and how businesses formulate their strategic plans. We generally categorize markets into four distinct types: Perfect Competition, Monopolistic Competition, Oligopoly, and Monopoly.
Perfect Competition: The Idealized Benchmark
Perfect competition represents a theoretical extreme where no single firm has the power to influence the market price. In this structure, there are a vast number of small firms, and every firm sells an identical (homogeneous) product. Because the products are exactly the same, consumers do not care which seller they buy from; they simply seek the lowest price.
Key characteristics include:
Many Buyers and Sellers: No individual participant can influence the market price by changing their own quantity supplied or demanded.
Homogeneous Products: Goods are perfect substitutes for one another.
Perfect Information: All buyers and sellers have complete knowledge of prices and technology.
Freedom of Entry and Exit: Firms can enter or leave the industry without significant barriers.
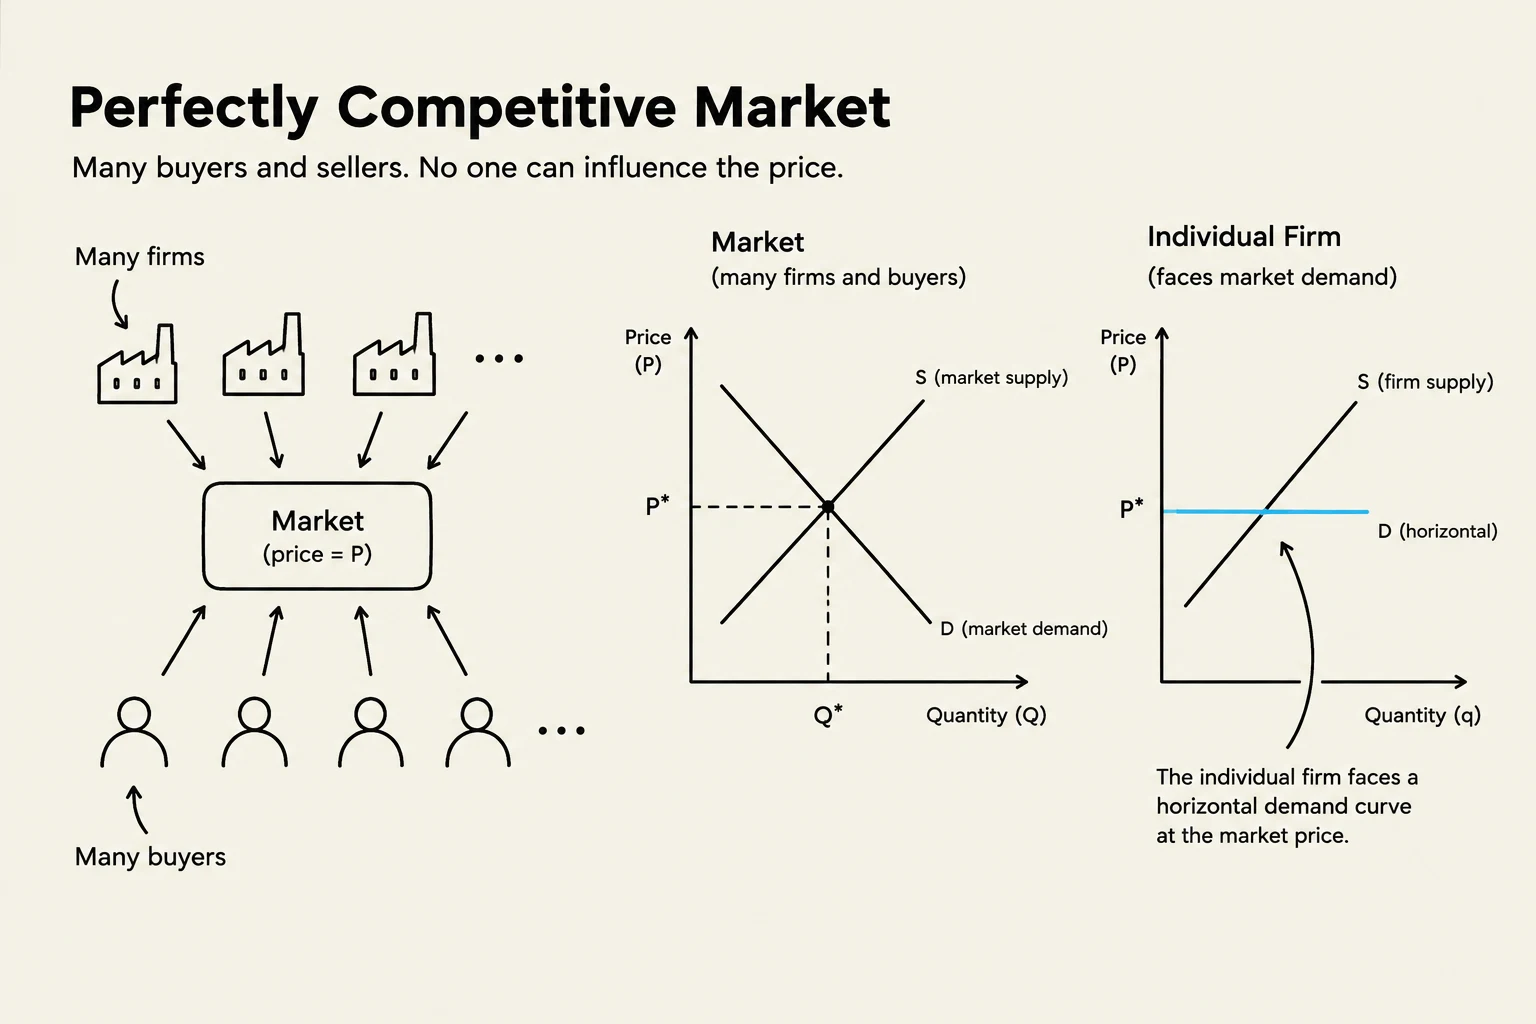
In this environment, firms are "price takers." If the market price for wheat is $5 per bushel, a single farmer cannot sell it for $5.05 because buyers will immediately switch to a competitor.
This diagram illustrates a perfectly competitive market, showing the interaction of many buyers and sellers. It depicts the market equilibrium price and quantity, and how an individual firm in such a market faces a horizontal demand curve at the market price.
Exam Tip: Remember that in the long run, firms in perfect competition earn zero economic profit. If firms start making high profits, new competitors will enter the market, increasing supply and driving the price back down until profits are normalized.
Monopolistic Competition: The Reality of Branding
While perfect competition is rare in the real world, monopolistic competition is incredibly common. This structure describes industries where many firms compete, but they do so by selling products that are slightly different from one another. This difference is known as product differentiation.
Product differentiation can be achieved through:
Physical differences: Quality, features, or design.
Location: Being the only coffee shop on a specific street corner.
Branding/Perception: Using advertising to make a consumer believe a product is superior.
Because their products are not identical, firms in monopolistic competition have a small degree of "market power." They are not pure price takers; if a brand like Nike raises the price of a specific sneaker slightly, they won't lose all their customers, because some customers are loyal to the brand.
Oligopoly: The Power of a Few
An oligopoly exists when a market is dominated by a small number of large firms. Unlike monopolistic competition, where there are many players, an oligopoly is characterized by interdependence. This means that the actions of one firm (like changing a price or launching a massive ad campaign) directly affect and provoke reactions from its competitors.
Common features of an oligopolies include:
High Barriers to Entry: It is difficult for new firms to enter due to high startup costs, patents, or control of resources.
Strategic Behavior: Firms must constantly watch their rivals.
Non-Price Competition: Instead of engaging in "price wars" that hurt everyone's profits, firms often compete through advertising, loyalty programs, and product improvements.
Examples of oligopolies include the commercial aircraft industry (Boeing and Airbus) or the wireless carrier industry (Verizon, AT&T, T-Mobile).
Note on Collusion: In some oligopolies, firms may attempt to act like a single monopoly by coordinating prices. This is known as collusion. In many jurisdictions, such as the United States, collusion is illegal under antitrust laws because it harms consumers.
Monopoly: The Single Seller
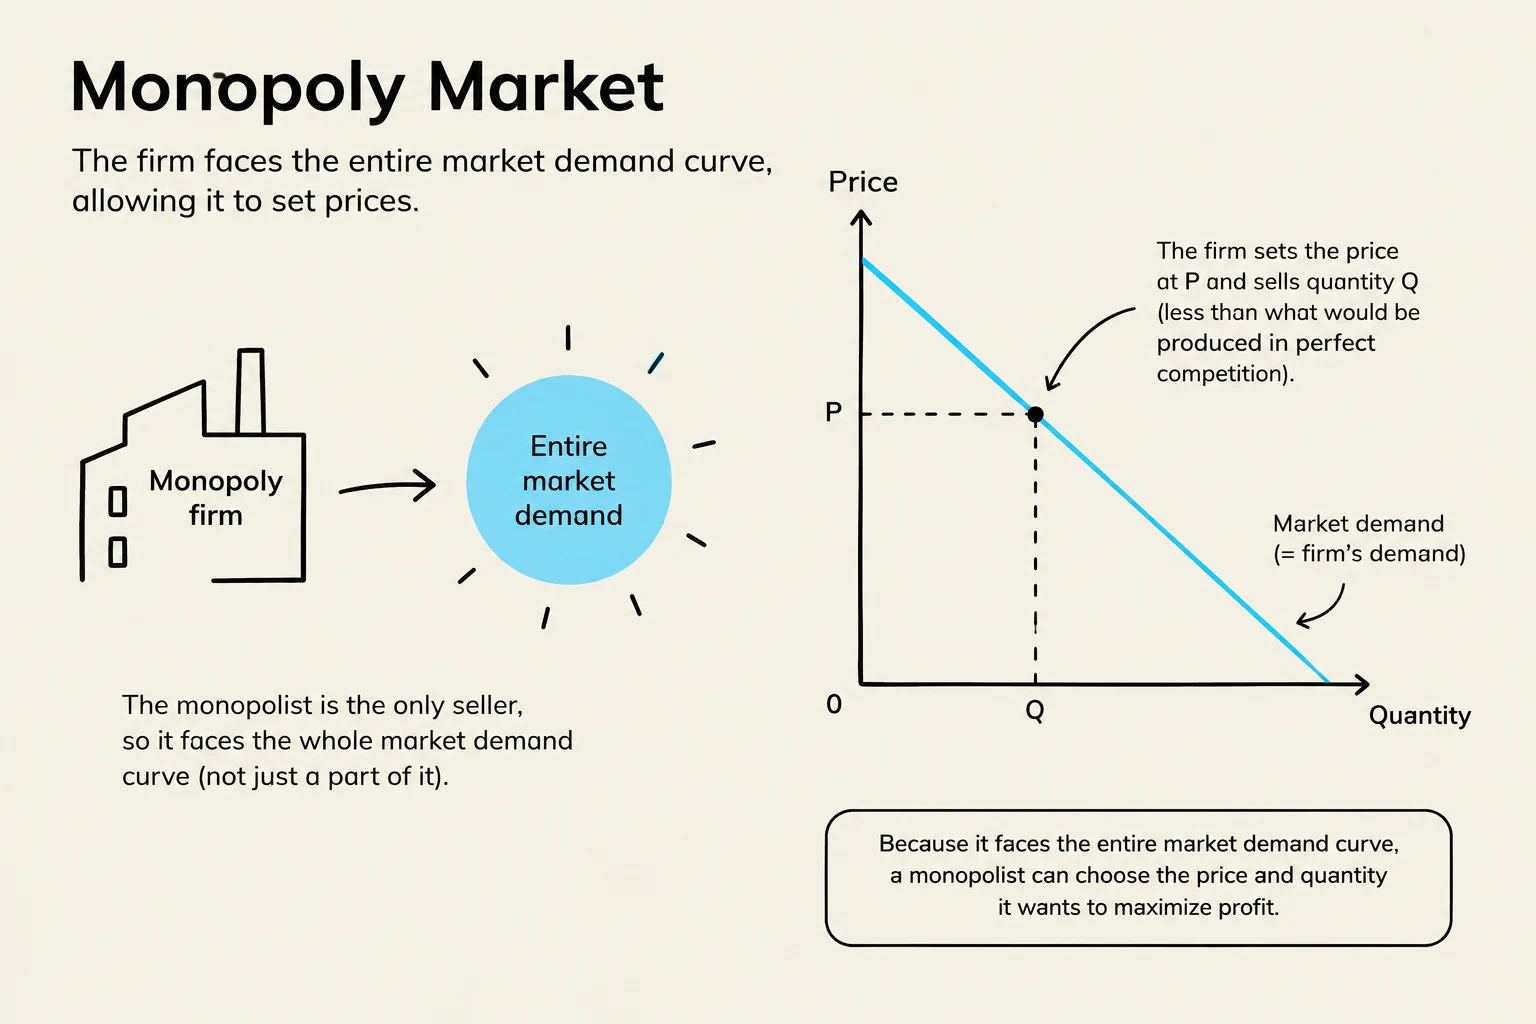
A monopoly is the polar opposite of perfect competition. In a monopoly, a single firm is the sole provider of a product or service for which there are no close substitutes. Because there is no competition, the firm is a "price maker."
A monopoly can be maintained through several types of barriers to entry:
Legal Barriers: Patents, copyrights, or government licenses.
Control of Resources: Owning the entire supply of a raw material.
Economies of Scale: A "natural monopoly" occurs when a single firm can produce the entire market's output at a lower cost than two or more firms could (e.g., a local water utility company).
This diagram illustrates the concept of a monopoly market, where a single firm faces the entire market demand curve and can set prices to maximize profit.
Summary Comparison Table
To help synthesize these concepts, consider the following comparison of the four market structures:
Feature
Perfect Competition
Monopolistic Competition
Oligopoly
Monopoly
Number of Firms
Very Many
Many
A Few Large Firms
One
Type of Product
Identical
Differentiated
Identical or Differentiated
Unique
Price Control
None (Price Taker)
Some
Significant
High (Price Maker)
Barriers to Entry
None
Low
High
Very High
Example
Agriculture (Wheat)
Restaurants / Clothing
Automobiles / Airlines
Local Utility Company
By understanding these structures, economists can better evaluate the efficiency of markets and the necessity of government intervention to protect consumers from unfair pricing or lack of choice.
Keep reading for free.
Create an account to finish this reading and make it part of your study routine.