Understanding Externalities and Market Failure in Economics
This content explains externalities as side effects of economic activities that impact bystanders, leading to market failure when private interests diverge from societal interests. It details negative and positive externalities, their impact on production, and the economic concepts of marginal private and social costs
In a perfect market, the decisions made by buyers and sellers lead to efficient outcomes for everyone involved. However, real-world markets often encounter "side effects" that impact people who are not part of the transaction. These side effects are known as externalities. When these effects occur, the interests of the individuals making the decisions (private interests) diverge from the interests of the community (society's interest), leading to a phenomenon known as market failure.
Understanding Externalities
An externality is a side effect of an activity that affects bystanders whose interests are not taken into account in the decision-making process. Because these bystanders are ignored or underweighted, the market fails to reach an efficient outcome.
Negative Externalities
A negative externality occurs when a choice imposes a cost on others. Common examples include the pollution caused by burning fossil fuels, secondhand smoke from smoking, or the traffic congestion caused by an individual's decision to drive. Because the person performing the action does not pay for these external costs, they tend to do too much of the harmful activity relative to what is best for society.
Positive Externalities
A positive externality occurs when a choice generates a benefit for others. For instance, if you plant a beautiful garden, your neighbors enjoy the view; if you get a vaccine, you reduce the risk of spreading disease to others. Because people often ignore the benefits they provide to bystanders, they tend to do too little of these beneficial activities.
Exam Tip: Remember the direction of market failure!
The Economic Math: Private vs. Social Costs and Benefits
To understand why markets fail, we must distinguish between private and social values using marginal analysis.
Analyzing Negative Externalities
When a firm produces a good, it considers its own costs, but society bears additional costs.
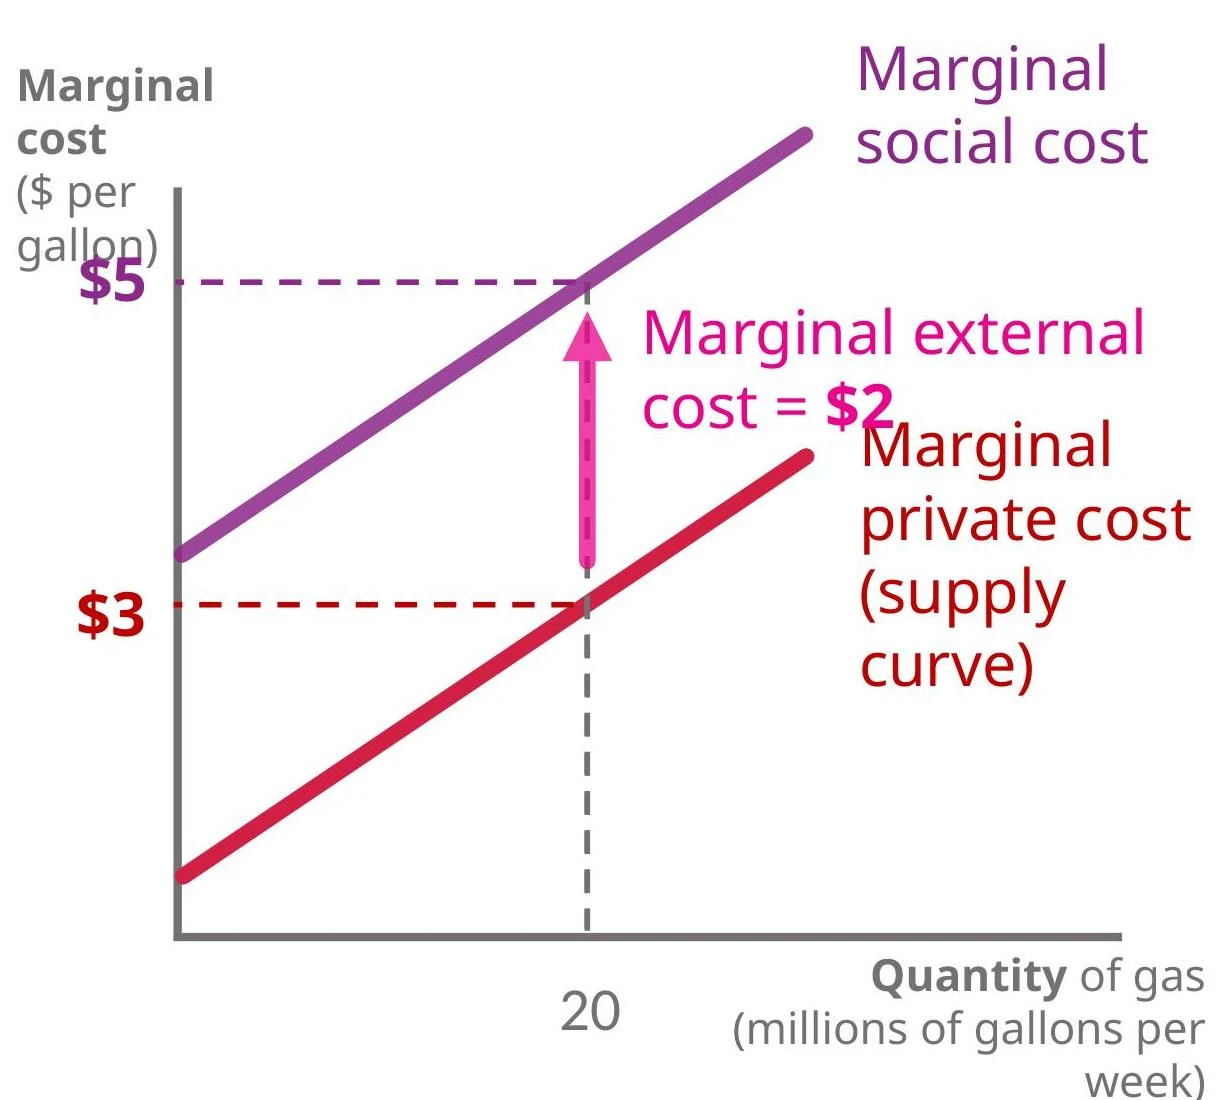
Marginal Private Cost (MPC): The extra cost paid by the seller to produce one more unit (e.g., labor and materials). This represents the firm's supply curve.
Marginal External Cost (MEC): The extra cost imposed on bystanders (e.g., pollution).
Marginal Social Cost (MSC): The total cost to society, calculated as:
$MSC = MPC + MEC$
This graph illustrates the concept of marginal cost in economics, showing the marginal private cost (supply curve) and the marginal social cost, with the difference representing the marginal external cost.
In a market with a negative externality, the equilibrium quantity is determined only by MPC and the buyer's benefit. Because the MSC is higher than the MPC, the market produces more than the socially optimal quantity.
Analyzing Positive Externalities
Similarly, for beneficial activities, the buyer's personal satisfaction is only part of the total benefit to society.
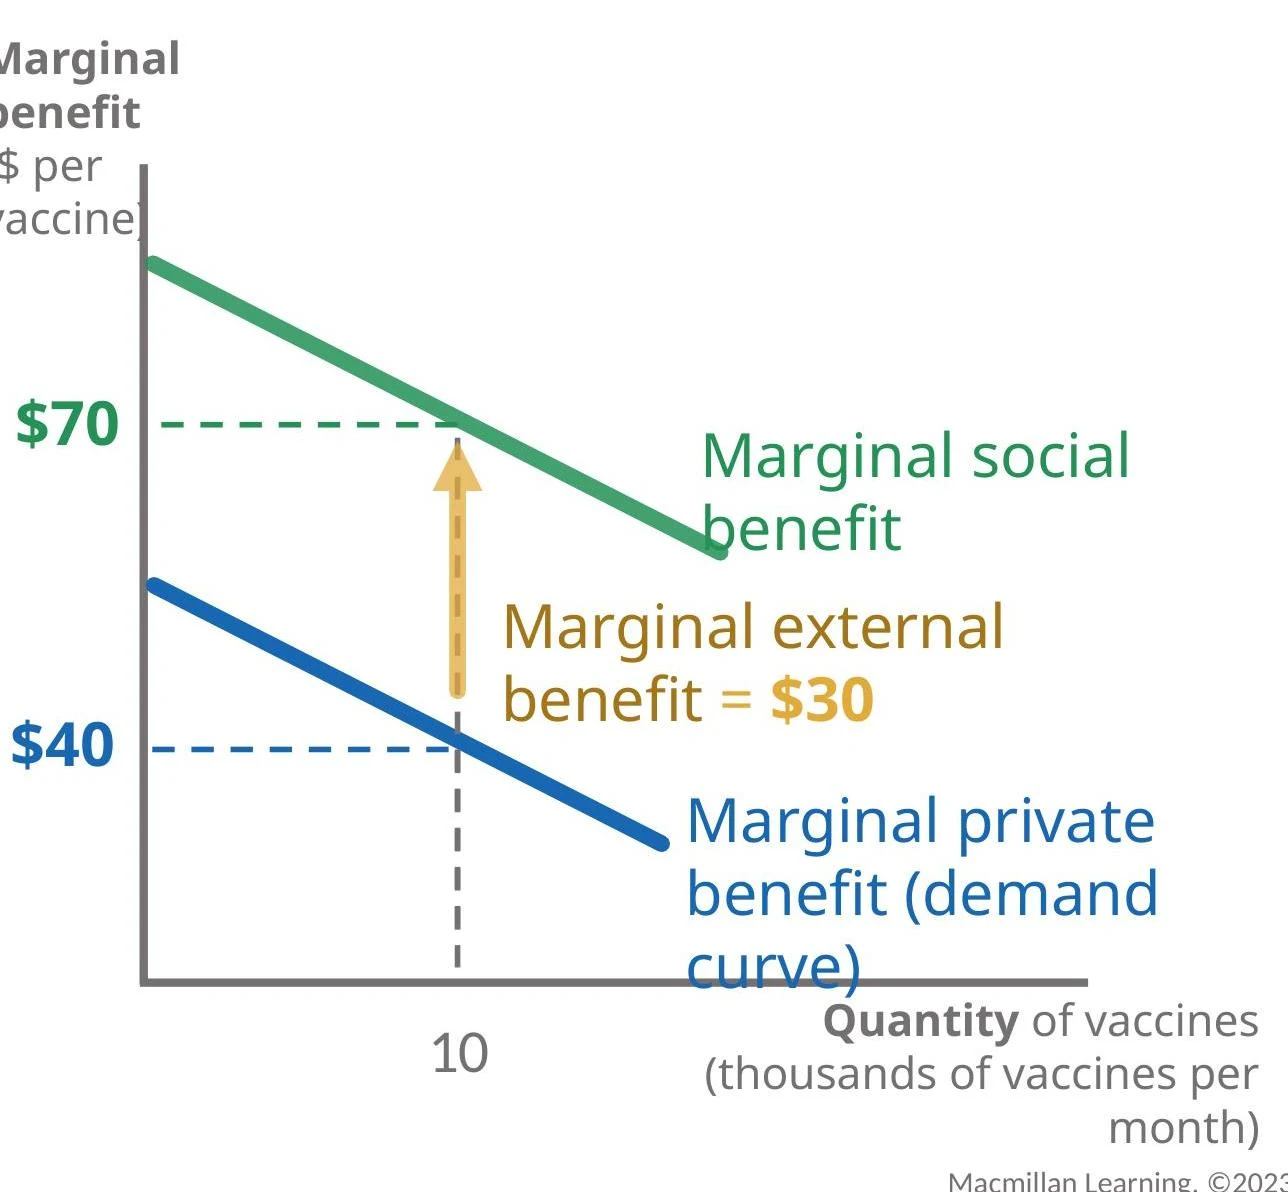
Marginal Private Benefit (MPB): The extra enjoyment or value received by the buyer (the demand curve).
Marginal External Benefit (MEB): The extra benefit accruing to bystanders.
Marginal Social Benefit (MSB): The total benefit to society, calculated as:
$MSB = MPB + MEB$
This graph illustrates the concept of marginal social benefit, which is the sum of marginal private benefit and marginal external benefit. The graph shows that the marginal social benefit is higher than the marginal private benefit, indicating a positive externality.
Because the MSB is higher than the MPB, the market underproduces the good, resulting in a quantity lower than the socially optimal level.
Finding the Socially Optimal Quantity
The socially optimal quantity is the level of production that is most efficient for society as a whole, accounting for all costs and benefits regardless of who pays or receives them.
To find this, economists use the marginal principle: society is better off producing an additional unit only if the marginal social benefit is at least as large as the marginal social cost. Therefore, the socially optimal quantity is located exactly where:
$MSB = MSC$
Solutions to Externality Problems
The goal of any solution is to internalize the externality, ensuring that people take the effects of their actions on bystanders into account.
1. Private Bargaining (The Coase Theorem)
If property rights are clearly defined and bargaining is costless (meaning it is easy to reach a deal without expensive legal battles), private parties can negotiate to reach the optimal outcome. This can involve side payments: a person harmed by an action might pay someone to stop, or a person benefiting from an action might pay someone to do more.
2. Corrective Taxes and Subsidies
When bargaining is too difficult (such as with global climate change), the government can intervene:
Corrective Tax: For negative externalities, a tax is set equal to the MEC to make the producer feel the full cost of their actions.
Corrective Subsidy: For positive externalities, a subsidy is set equal to the MEB to encourage more of the beneficial activity.
3. Cap and Trade
This is a quantity-based regulation where the government sets a maximum limit (a cap) on pollution and issues permits. Firms can trade these permits; efficient firms that can reduce pollution cheaply will buy permits from less efficient firms, concentrating production among the cleanest businesses.
4. Laws, Rules, and Regulations
Governments often use direct mandates, such as noise restrictions, speeding laws, or fuel efficiency regulations, to limit harmful behaviors.
Special Cases: Public Goods and Common Resources
Externalities are particularly intense when goods are nonexcludable (meaning you cannot easily stop people from using them).
Public Goods (Nonrival & Nonexcludable): These goods, like national defense or public education, suffer from the free-rider problem, where people enjoy the benefits without paying. This leads to underproduction. The solution is often direct government provision using tax money.
Common Resources (Rival & Nonexcludable): These goods, like fish in the ocean, lead to the tragedy of the commons, where individuals overconsume the resource because they reap the private benefits but share the costs with everyone else. A common solution is to assign ownership rights, giving someone an incentive to manage the resource sustainably.
Keep reading for free.
Create an account to finish this reading and make it part of your study routine.