


Navigating the landscape of corporate governance and auditing in Malaysia requires a clear understanding of the interplay between statutory laws, ethical codes, and the specific duties of various stakeholders. For students and professionals alike, mastering these concepts is essential for ensuring transparency and accountability within the corporate sector. This article explores the regulatory framework established by the Malaysian Code on Corporate Governance 2021 and the Companies Act 2016, while detailing the distinct roles of directors, auditors, and oversight bodies.
The Governance Framework: MCCG 2021 and the Audit Function
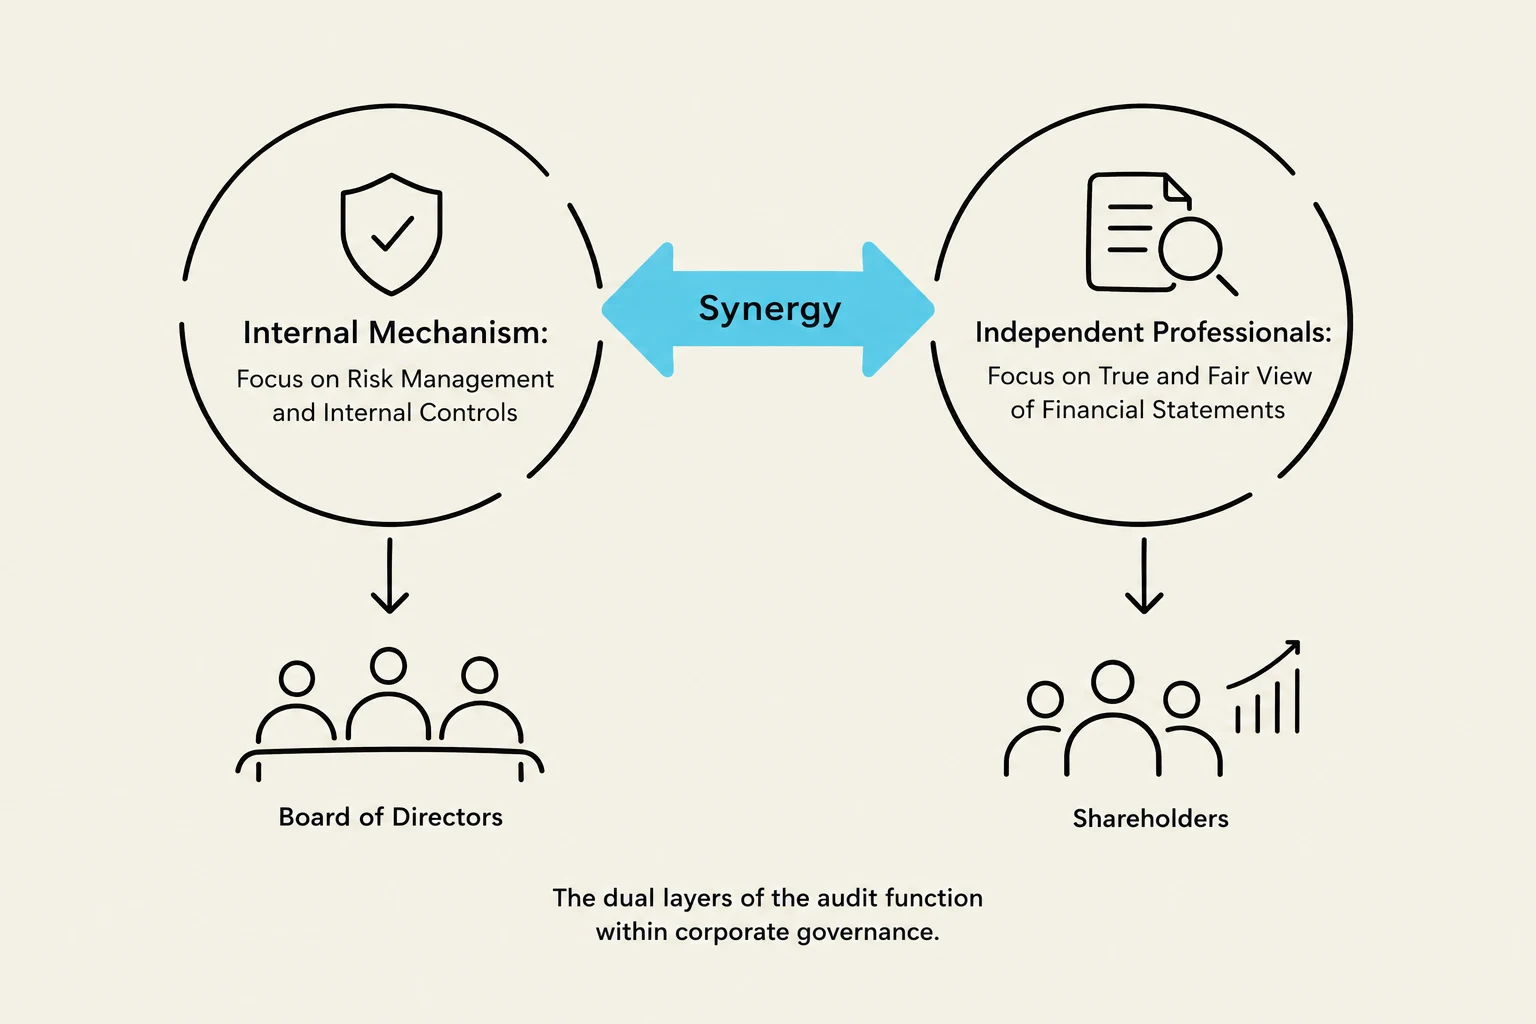
Within this framework, two distinct but complementary audit functions exist:
- External Auditors: These are independent professionals appointed to provide an objective opinion on whether a company's financial statements present a true and fair view of its financial position.
- Internal Audit Function: This is an internal mechanism designed to provide independent assurance to the board that the company's risk management, governance, and internal control processes are operating effectively.
The MCCG 2021 highlights that a strong corporate governance structure relies on the synergy between these two functions to ensure that information flowing to the board is both accurate and reliable.
The Legal Backbone: Companies Act 2016
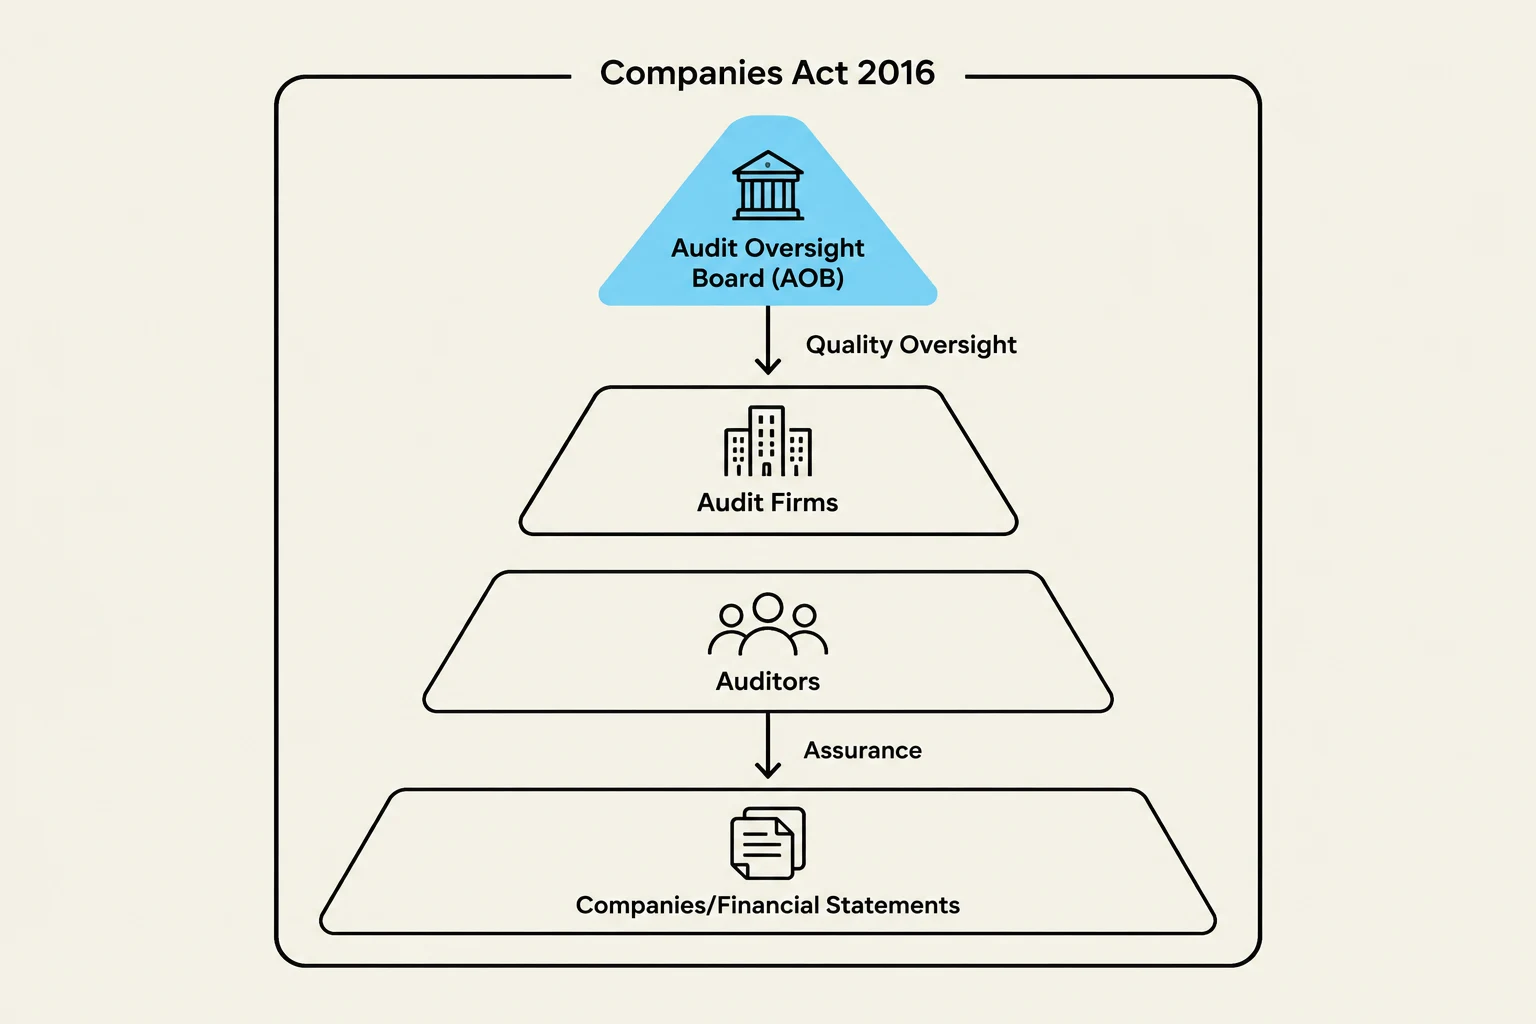
While the MCCG provides best practices, the Companies Act 2016 provides the legal mandate. It dictates the statutory requirements for companies operating in Malaysia, including the necessity of conducting audits for certain entities.
Keep reading for free.
Create an account to finish this reading and make it part of your study routine.
Continue reading freeAlready have an account? Log in
Updated