Explores the economic concept of asymmetric information, where one party in a transaction has more knowledge than the other. Covers adverse selection and moral hazard, with examples in insurance, labor, and used car markets. Discusses mitigation strategies like signaling, screening, and incentive alignment.
In a perfect economic model, every participant has access to the same information. Buyers know exactly what a product is worth, and sellers know exactly how much it costs to produce. However, the real world rarely functions this way. In almost every transaction, one party possesses more or better information than the other. This phenomenon is known as asymmetric information.
When one party holds a "knowledge advantage," the natural equilibrium of the market can be disrupted, leading to inefficiencies, unfair pricing, or even the total collapse of a market. Understanding this imbalance is crucial for grasping how modern economies, legal systems, and professional relationships function.
The Core Concept: The Knowledge Gap
At its simplest level, asymmetric information occurs when there is a disparity in the quality or quantity of information held by the participants in a transaction. This is not merely about "knowing more"; it is about the inability of the uninformed party to verify the claims made by the informed party.
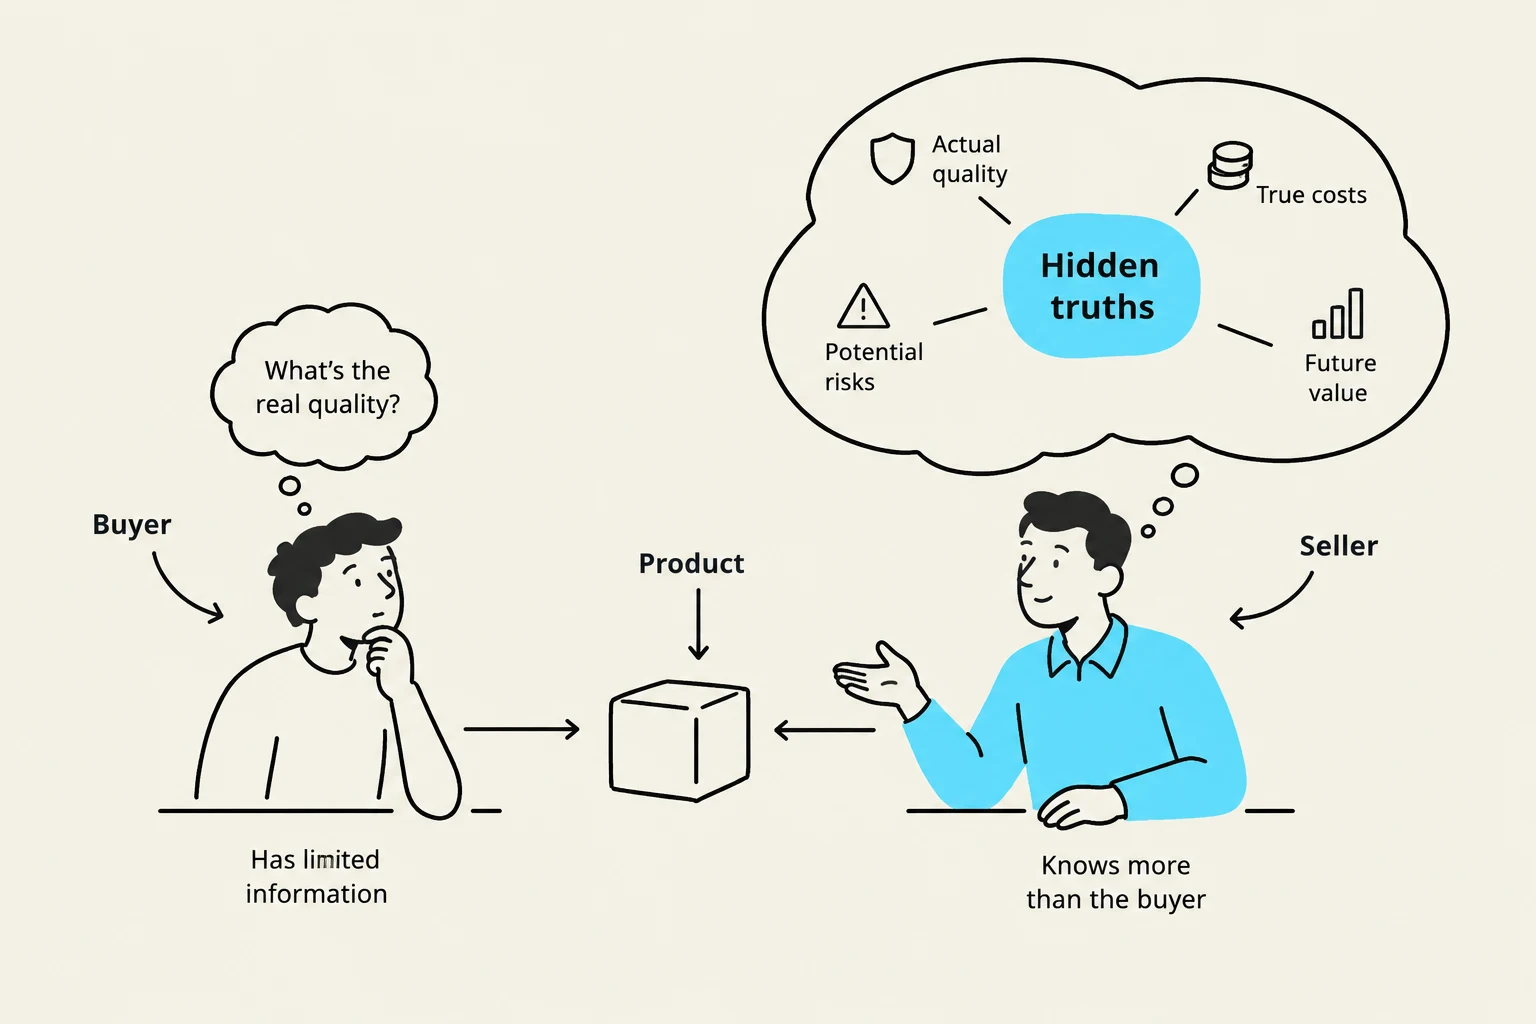
Consider the classic example of a used car sale. A seller knows if a car has been in a major accident or if the engine has a recurring fault. The buyer, looking at the shiny exterior, cannot easily discern these hidden truths. This gap creates a fundamental tension: the buyer wants to pay a fair price, but because they cannot verify the car's true condition, they are hesitant to pay a premium.
This diagram illustrates the concept of asymmetric information in a transaction, where the seller possesses more knowledge about the product's true quality, costs, and future value than the buyer, who has limited information and may question the real quality.
Exam Tip: When defining asymmetric information, always distinguish between "hidden characteristics" (what a product is) and "hidden actions" (what a person does). This distinction is the foundation for the two main problems: Adverse Selection and Moral Hazard.
Adverse Selection: The Problem of Hidden Characteristics
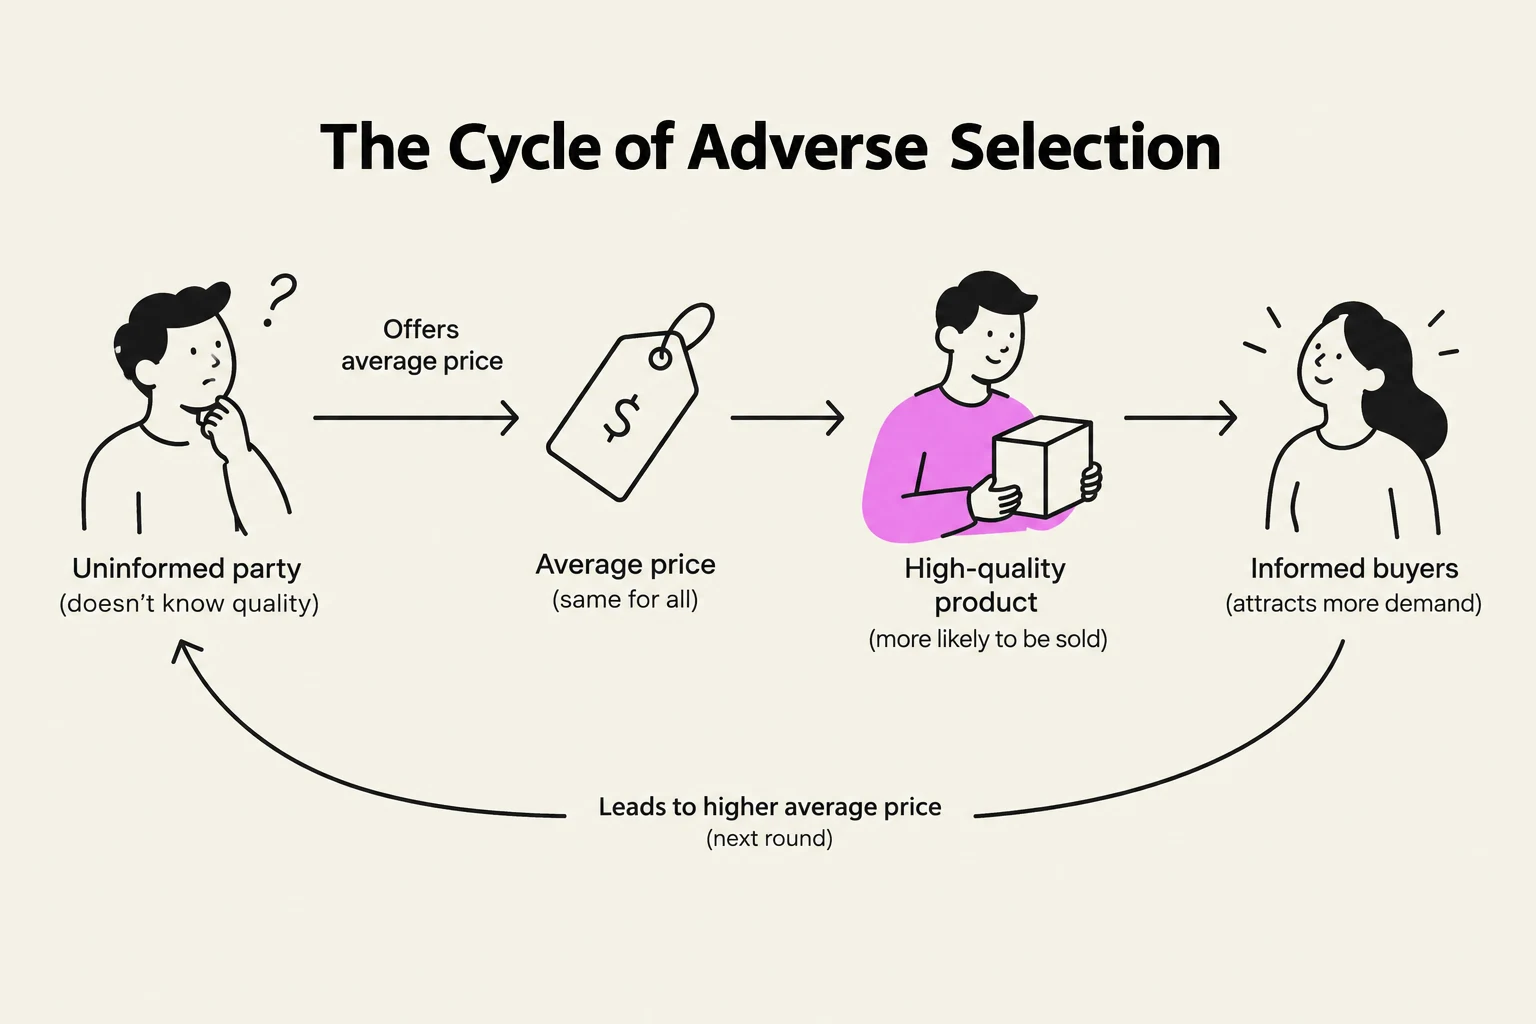
Adverse selection occurs before a contract is signed or a transaction is completed. It arises when the uninformed party cannot distinguish between high-quality and low-quality participants, leading them to offer an "average" price.
In the used car market, if buyers cannot tell a "lemon" (a bad car) from a "peach" (a good car), they will only be willing to pay an average price. This average price is too low for owners of "peaches" to accept, so they withdraw their high-quality cars from the market. Consequently, only the "lemons" remain. This is a self-reinforcing cycle where the market becomes flooded with low-quality goods.
This concept extends far beyond car sales:
Insurance Markets: An individual knows they have a high-risk lifestyle (e.g., extreme sports) that an insurance company cannot easily see. If the insurer charges a standard premium, the high-risk individuals will flock to the insurance, while low-risk individuals will find it too expensive and leave.
Labor Markets: An applicant knows their true work ethic, but an employer only sees a resume. If an employer offers a mediocre wage to account for potential laziness, the most talented and hardworking candidates may seek better-paying competitors, leaving the employer with a pool of less capable workers.
This diagram illustrates the cycle of adverse selection in economics, where uninformed parties offer an average price for products, leading to a situation where only high-quality products are likely to be sold, attracting more demand from informed buyers and ultimately leading to a higher average price in subsequent rounds.
Moral Hazard: The Problem of Hidden Actions
While adverse selection deals with what people are, moral hazard deals with what people do. Moral hazard occurs after a transaction has taken place. It happens when one party takes risks or changes their behavior because they know the costs of those risks will be borne by someone else.
The most common example is insurance. Once a person has comprehensive theft insurance for their car, they might become less diligent about locking the doors or parking in secure areas. The "cost" of their carelessness is shifted to the insurance company.
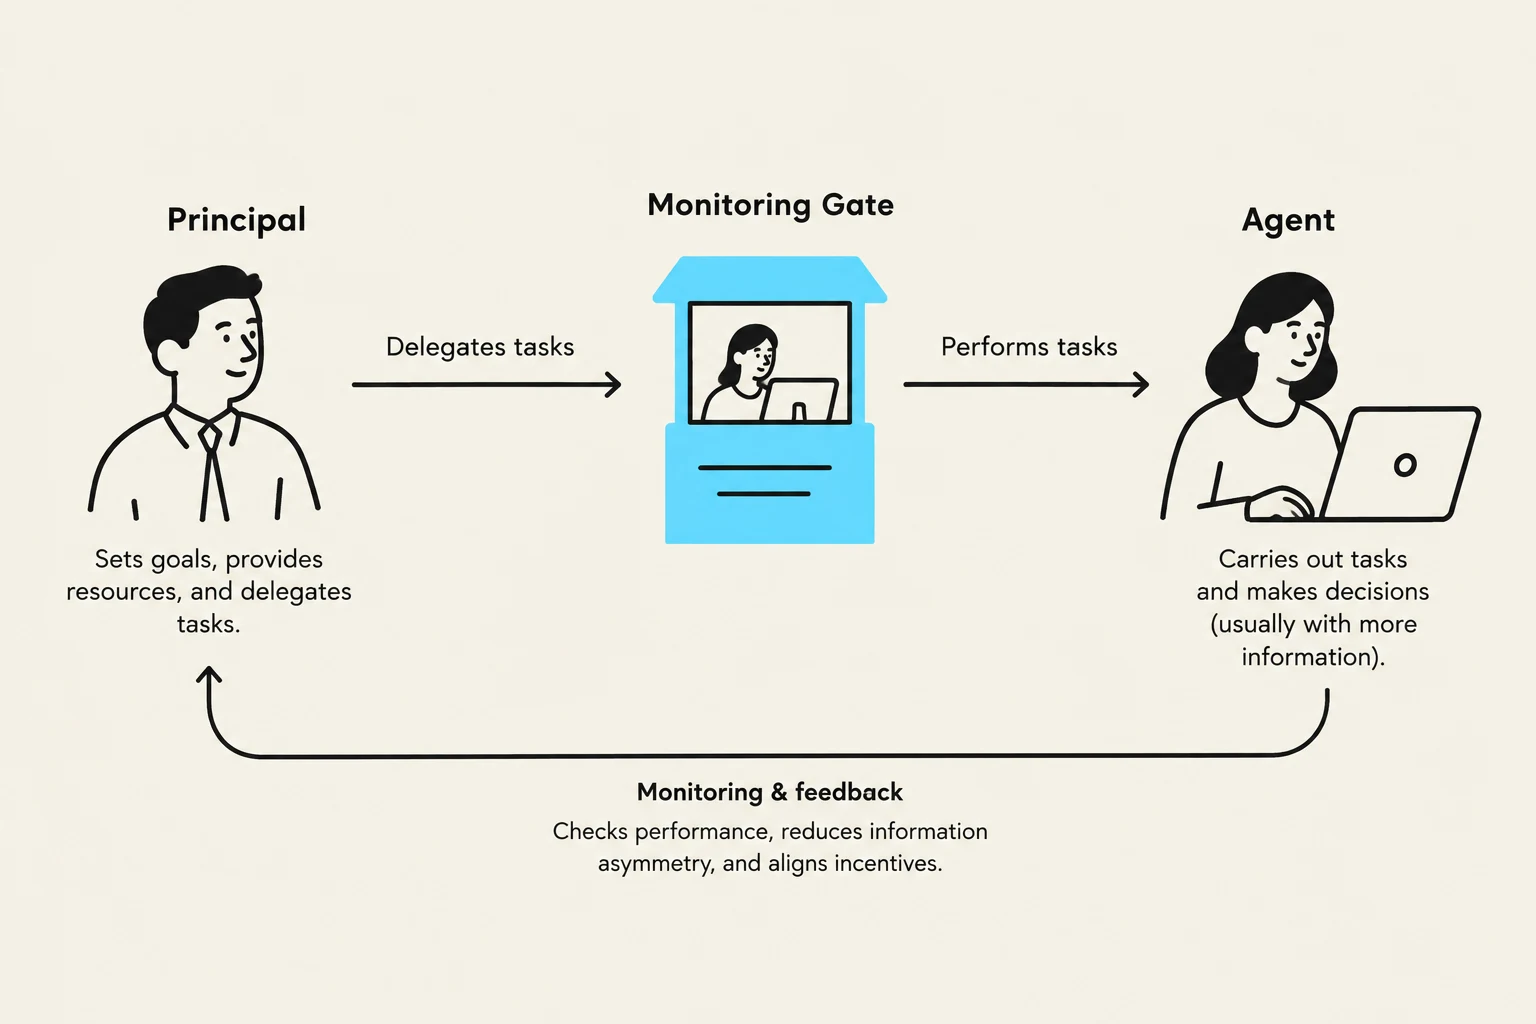
In a professional or political context, this manifests as the Principal-Agent Problem. This occurs when a "principal" (someone who hires or delegates authority) employs an "agent" (someone who acts on their behalf).
The Principal-Agent Problem in Bureaucracy
In large organizations or government structures, the principal (the public or a CEO) wants the agent (a bureaucrat or manager) to act in the principal's best interest. However, the agent often has different incentives. Because the principal cannot monitor every single action the agent takes, the agent may engage in "shirking" (doing the bare minimum) or "empire building" (expanding their department's size and budget to increase their own power, even if it doesn't benefit the organization).
The mathematical tension can be viewed as a divergence in utility functions. If Up is the utility of the principal and Ua is the utility of the agent:
Goal of Principal: Goal of Agent: maxUp(Actionoptimal)maxUa(Actionself−serving)
Where Actionoptimal=Actionself−serving due to the lack of perfect monitoring.
This diagram illustrates the principal-agent problem in economics, showing how a principal delegates tasks to an agent, who performs them, with a monitoring gate in between to check performance and provide feedback.
Mitigating the Imbalance
Economies have developed several mechanisms to reduce the friction caused by asymmetric information:
Signaling: The informed party takes an action to "signal" their quality to the uninformed party. For example, a student earns a degree to signal intelligence and discipline to an employer, or a car seller provides a certified vehicle history report.
Screening: The uninformed party takes steps to extract information. An insurance company might require a medical exam before issuing a policy to "screen" for high-risk health conditions.
Warranties and Guarantees: By offering a warranty, a seller provides a "signal" that they are confident in the product's quality. If the product were a "lemon," the cost of honoring the warranty would be too high for the seller.
Incentive Alignment: To solve the Principal-Agent problem, principals use performance-based pay. In a corporation, giving managers stock options aligns their interests with the shareholders; if the company does well, both the agent and the principal benefit.
Summary Table
Feature
Adverse Selection
Moral Hazard
Timing
Before the transaction
After the transaction
Core Issue
Hidden characteristics (What it is)
Hidden actions (What they do)
Example
A buyer cannot tell if a car is a "lemon"
A driver becomes reckless because they are insured
Solution
Signaling and Screening
Monitoring and Incentive Alignment
By recognizing these imbalances, we can better understand why markets sometimes fail and how legal and economic structures are designed to restore trust and efficiency.
Keep reading for free.
Create an account to finish this reading and make it part of your study routine.