Regulation of Broker-Dealers and Agents Under the Uniform Securities Act
An overview of the Uniform Securities Act (USA) and its framework for regulating broker-dealers and agents at the state level, covering definitions, registration requirements, and post-registration compliance.
The regulation of securities professionals is a cornerstone of investor protection under the Uniform Securities Act (USA). While federal laws like the Securities Exchange Act of 1934 govern national markets, the USA provides the framework for state-level regulation, ensuring that those who facilitate the buying and selling of securities are properly registered, financially stable, and ethically sound. This article explores the definitions, registration requirements, and post-registration responsibilities for broker-dealers and agents.
Defining the Players: Broker-Dealers and Agents
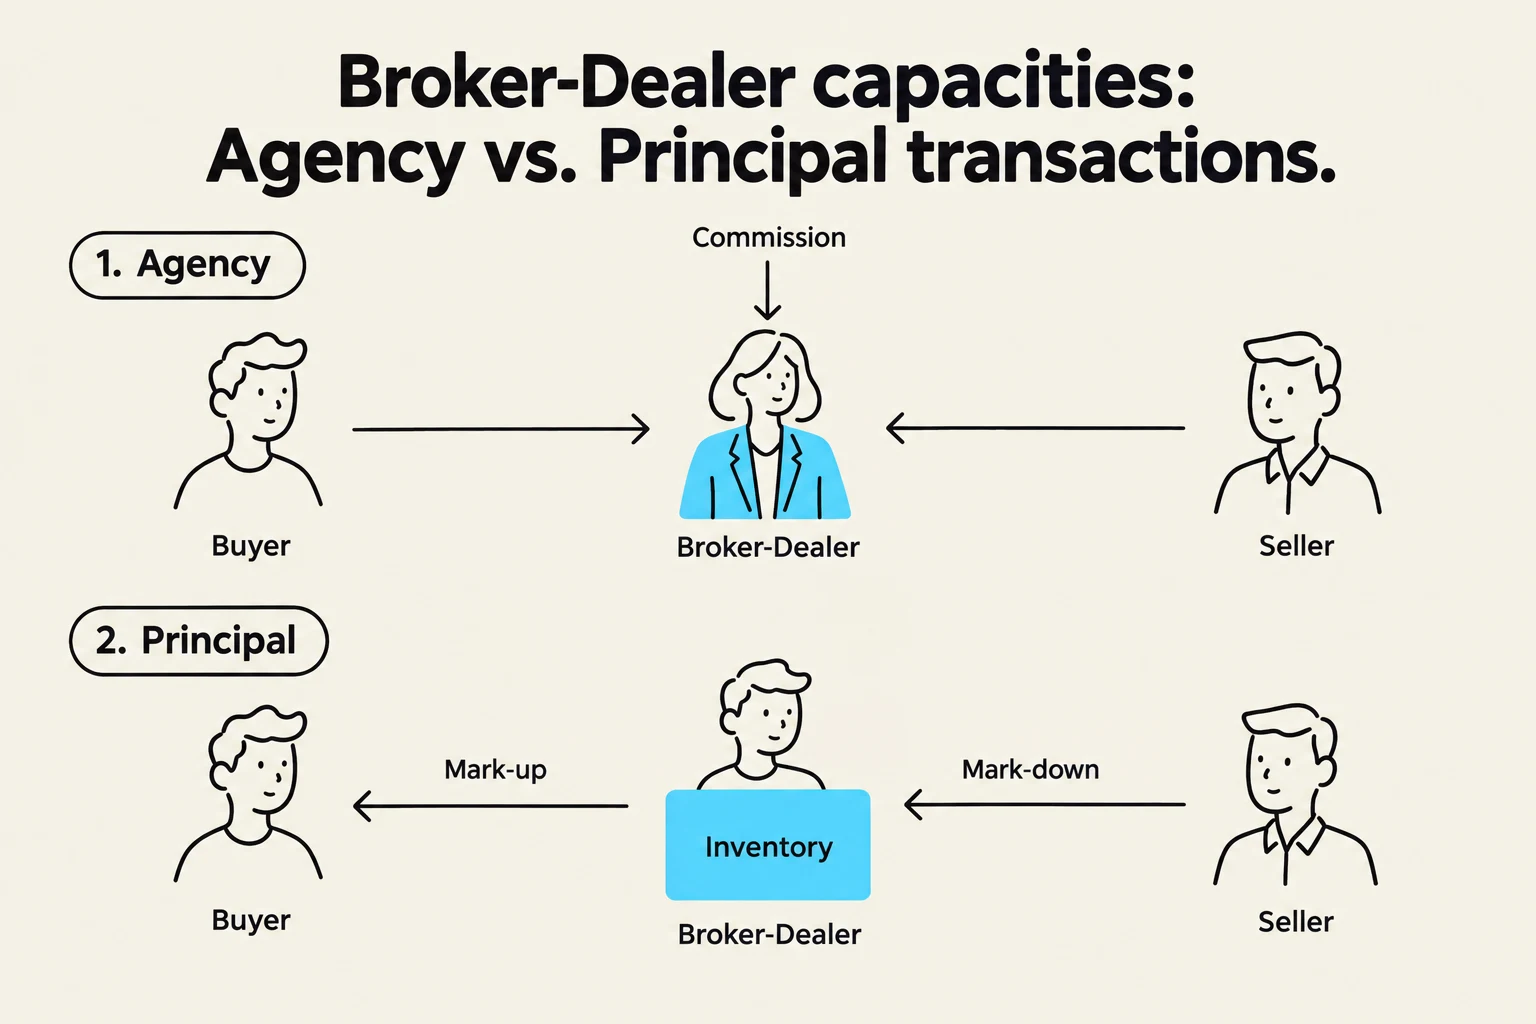
This diagram illustrates the difference between agency and principal transactions for a broker-dealer. In an agency transaction, the broker-dealer acts as an intermediary, facilitating a commission-based transaction between a buyer and a seller. In a principal transaction, the broker-dealer acts as a principal, buying and selling inventory from and to buyers and sellers, with mark-ups and mark-downs.
To navigate state law, one must first distinguish between the legal entities (firms) and the natural persons (individuals) involved in transactions.
Broker-Dealers (BDs)
A broker-dealer is a "person" (typically a legal entity like a corporation or partnership) engaged in the business of effecting securities transactions for its own account or for the accounts of others. BDs operate in two primary capacities:
Agency Transactions: The BD acts as a "broker," matching a buyer and a seller. In this role, the BD does not own the security and earns a commission.
Principal Transactions: The BD acts as a "dealer," trading from its own inventory. When selling from inventory, the BD charges a mark-up; when buying for inventory, it takes a mark-down.
Agents
An agent is a natural person representing a broker-dealer or an issuer in effecting securities transactions. It is important to note that an individual trading solely for their own personal account is not considered a broker-dealer.
Exam Tip: The "Person" Distinction
On the exam, remember that "person" is a broad term that can mean a legal entity (like a BD) or a natural person (like an agent). However, in the context of the USA, Broker-Dealers are almost always firms, while Agents are always individuals.
Registration Requirements
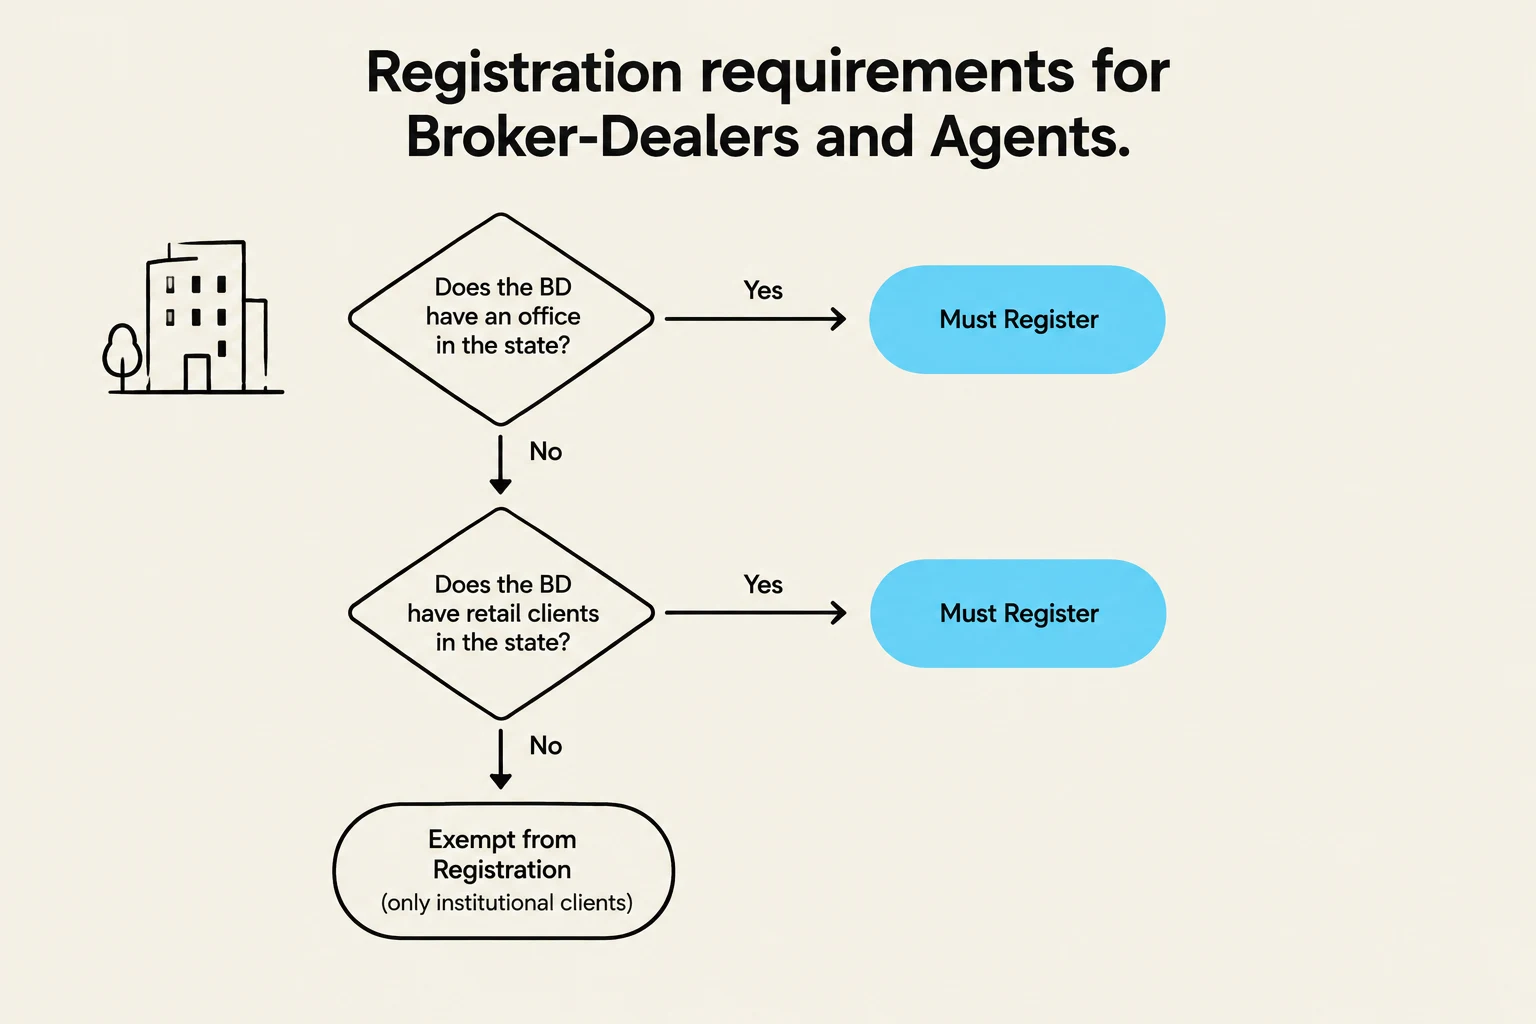
Flowchart outlining registration requirements for broker-dealers and agents, indicating when registration is mandatory or if an exemption applies based on office presence and client type.
Registration is the mechanism by which the State Administrator ensures that professionals meet minimum standards before interacting with the public.
Broker-Dealer Registration
A BD must register in any state where it maintains an office or has at least one retail client. Retail investors are viewed as less sophisticated and require stronger protections. Conversely, if a BD only conducts business with institutional investors (such as banks, insurance companies, or pension funds) and has no office in the state, it may be exempt from registration.
The registration process involves filing Form BD electronically via the Central Registration Depository (CRD). A key requirement for initial registration is the Consent to Service of Process, which allows the state administrator to receive legal documents on behalf of the firm.
Agent Registration
Agents must register in every state where they "transact business," which includes originating, directing, or accepting offers.
Agents of BDs: Must always be registered, regardless of the transaction type.
Agents of Issuers: May be exempt from registration if they are dealing exclusively with exempt securities or conducting exempt transactions.
For individual registration, agents use Form U4.
The Snowbird Exemption
If an agent travels to a different state to work with a client temporarily, they may be exempt from local registration for up to 30 days. If the client relocates to the agent's home state, the agent typically has 60 days to register in that state.
Post-Registration: Compliance and Financial Integrity
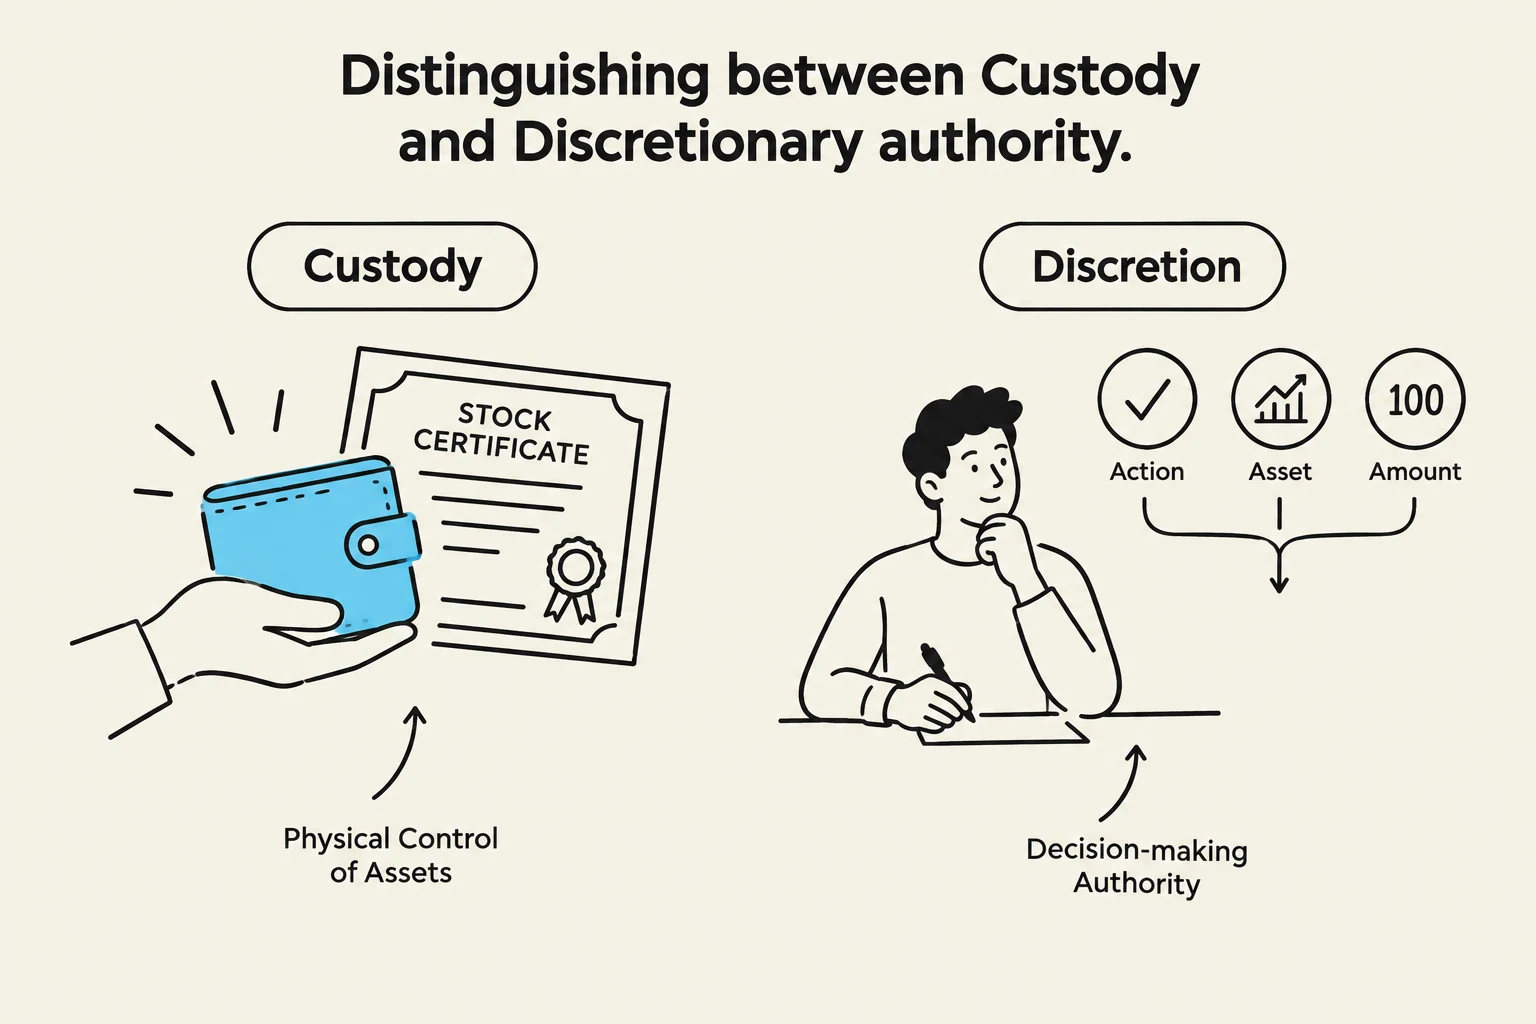
This illustration distinguishes between custody, representing physical control of assets like a stock certificate, and discretionary authority, which involves decision-making regarding actions, assets, and amounts.
Once registered, BDs and agents must adhere to ongoing rules regarding their finances and the authority they exercise over client accounts.
Financial Requirements: Net Capital and Bonds
To protect against insolvency, BDs must maintain minimum net capital (liquid assets) as prescribed by the SEC. Furthermore, firms that hold custody of client funds or possess discretionary authority may be required to post surety bonds (also known as fidelity bonds) to protect clients against theft or employee misconduct.
Custody vs. Discretion
These two concepts are frequently confused but have distinct legal definitions:
Custody: The physical holding or control of a client's funds or securities.
Discretion: The authority to make decisions regarding the "3 As" of a trade: Action (buy or sell), Asset (which security), or Amount (how many shares).
Note on Discretionary Orders
If an agent executes a trade but omits the specific time or price, this is considered a "not held" order. Such an order does not constitute discretionary authority.
Administrative and Ethical Considerations
The State Administrator has significant oversight, including the power to investigate and issue cease and desist orders.
Statutory Disqualification
A professional may face statutory disqualification if they have certain criminal convictions or have been subject to specific regulatory actions, which can prevent them from being registered or maintaining their current registration.
Successor Broker-Dealers
When a firm undergoes a change in ownership or structure, it may be treated as a successor broker-dealer, which can streamline certain aspects of the registration process under specific conditions.
Ministerial Transactions
Not every interaction with a client requires registration. Ministerial transactions—those that are purely clerical or administrative and do not involve investment advice or the execution of trades—are generally excluded from the definition of "transacting business".
Summary Table: Registration Overview
Entity
Primary Filing
Key Requirement
Broker-Dealer
Form BD
Net Capital & Consent to Service of Process
Agent
Form U4
Registration in every state where business is conducted
Keep reading for free.
Create an account to finish this reading and make it part of your study routine.