Measuring Net Exposure
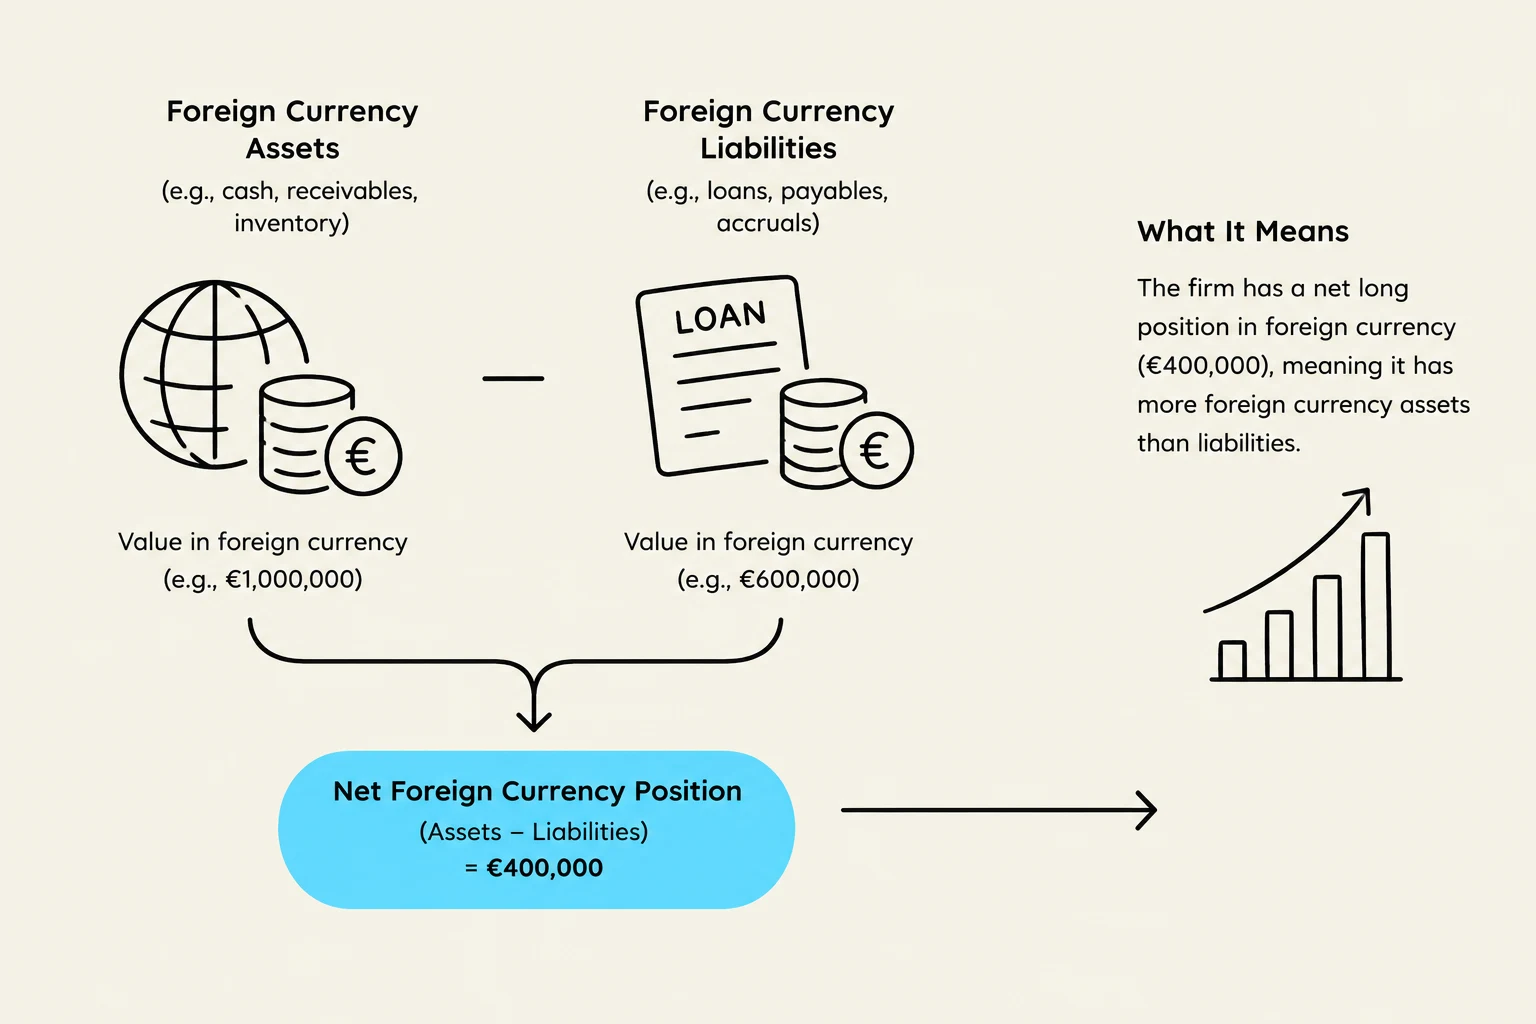
To manage risk, financial managers must calculate their Net Exposure. This is the difference between the total value of assets and the total value of liabilities in a specific foreign currency.
Let Af represent the value of assets in a foreign currency and Lf represent the value of liabilities in that same currency. The net exposure (E) in that currency is:
E=Af−Lf
If E>0, the firm has a net long position. If E<0, the firm has a net short position.
Exam Tip: When calculating net exposure for a consolidated balance sheet, always ensure you are looking at the same currency for both assets and liabilities. A common mistake is to mix the exposure of the Yen with the exposure of the Pound.
Worked Example: The Global Tech Corp
Suppose "Global Tech Corp" (reporting in USD) has the following positions in Japanese Yen (JPY):
- Cash in Tokyo: $¥100,000,000$
- Accounts Receivable (Japan): $¥50,000,000$
- Accounts Payable (Japan): $¥70,000,000$
- Long-term Debt (Japan): $¥30,000,000$
Step 1: Total JPY Assets
AJPY=100,000,000+50,000,000=150,000,000
Step 2: Total JPY Liabilities
LJPY=70,000,000+30,000,000=100,000,000
Step 3: Net Exposure
EJPY=150,000,000−100,000,000=+50,000,000 (Net Long)
If the Yen appreciates against the USD, Global Tech Corp will see an increase in its USD-denominated equity. If the Yen depreciates, the firm's value will decrease.
Impact on Firm Value
The primary goal of managing a multinational balance sheet is to protect the firm's value from unintended currency volatility. Exchange rate movements can create "paper" gains or losses that significantly impact the reported equity and net income of the firm.
There are two main ways these fluctuations impact the firm:
1. Translation Exposure (Accounting Exposure)
This is the risk that the value of the company's consolidated financial statements will change due to exchange rate fluctuations when translating foreign subsidiaries' accounts into the parent company's currency. While this often doesn't affect immediate cash flows, it can affect debt covenants and the perceived health of the company by investors.
2. Transaction Exposure (Economic Exposure)
This is the more tangible risk. It occurs when a firm has contractual obligations (like a pending invoice or a loan repayment) in a foreign currency. The actual amount of cash the firm receives or pays will change based on the exchange rate at the time the transaction is settled.
Strategic Management of the Balance Sheet
MNCs do not simply accept these risks; they actively manage them through several strategies:
- Matching: This involves structuring the balance sheet so that assets and liabilities in a specific currency are roughly equal, thereby neutralizing the net exposure.
- Leading and Lagging: This involves adjusting the timing of payments or receipts. If a firm expects a currency to appreciate, it might "lead" (pay early) its liabilities in that currency.
- Hedging: Using financial derivatives like forwards, futures, or options to lock in exchange rates for future transactions, effectively removing the uncertainty from the balance sheet.
By carefully balancing these elements, a multinational corporation can ensure that its global operations contribute to long-term value creation rather than becoming a victim of currency volatility.