This guide explains fundamental microeconomic principles including the distinction between microeconomics and macroeconomics, positive versus normative statements, and marginal cost-marginal benefit analysis. It is designed for introductory economics students.
Mastering the fundamentals of economics requires more than just memorizing definitions; it requires the ability to distinguish between different scales of analysis, differentiate between facts and opinions, and apply mathematical logic to decision-making. This study guide breaks down the core concepts found in the Chapter 1 practice problems, focusing on the distinction between micro and macroeconomics, the nature of economic statements, and the power of marginal analysis.
Microeconomics vs. Macroeconomics
The first step in economic analysis is determining the "lens" through which you are viewing the world. Economists generally divide the field into two broad categories: microeconomics and macroeconomics.
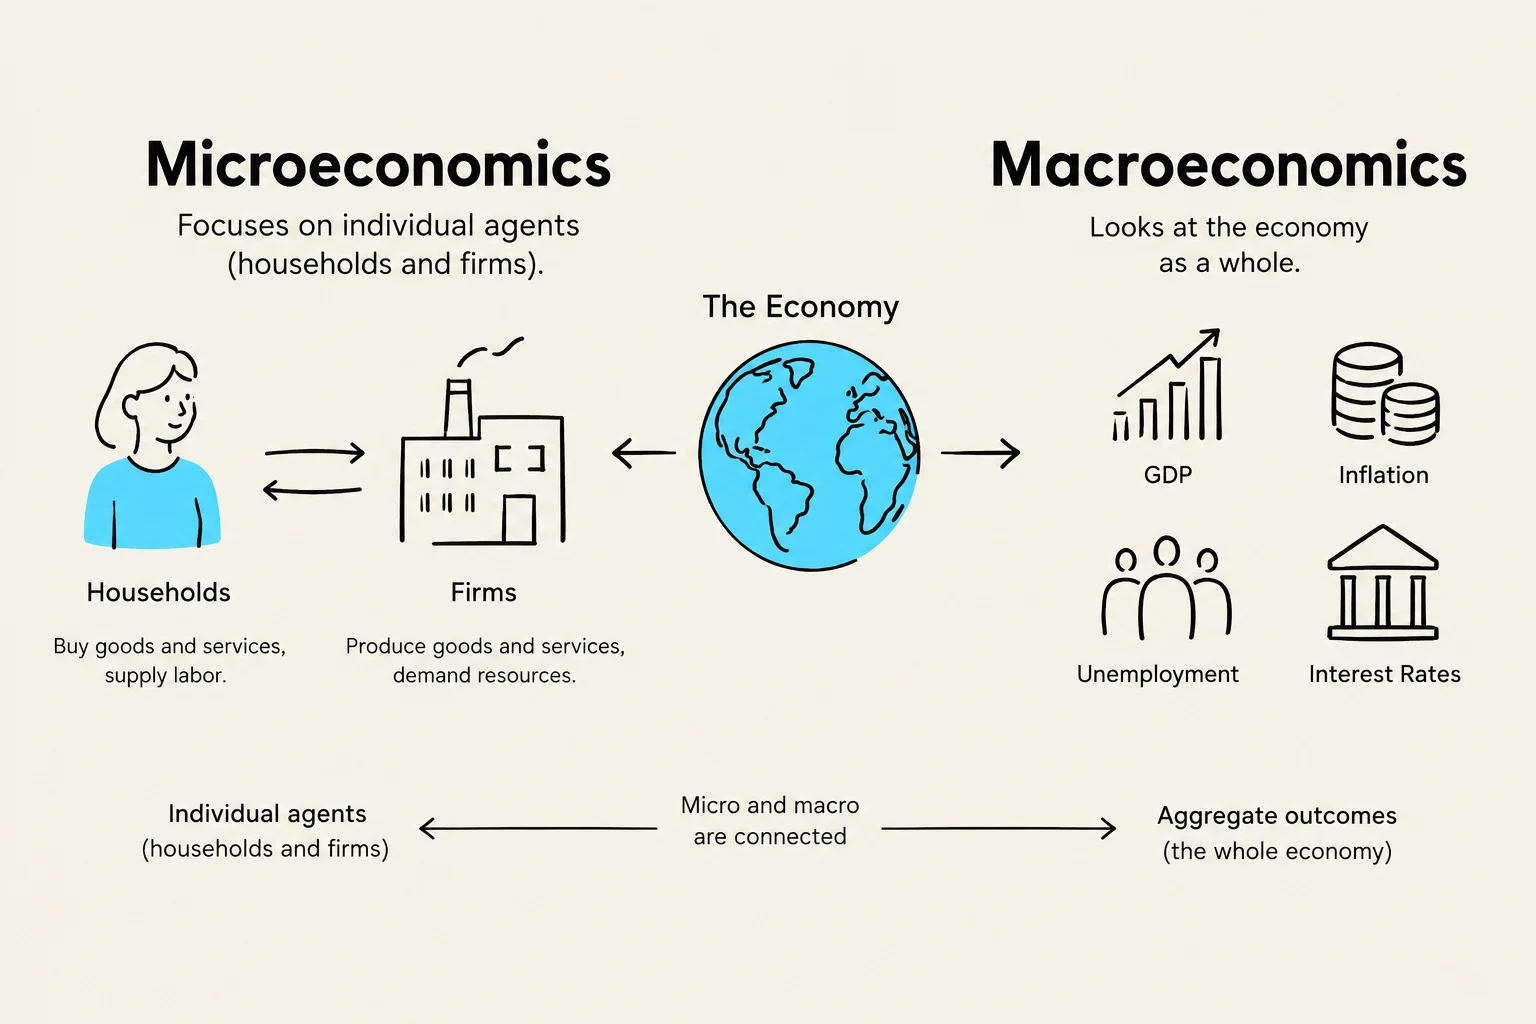
Microeconomics focuses on individual actors within the economy. This includes single consumers, specific households, or individual firms. When we look at how a specific company makes decisions—such as how many workers a dog food plant in Iowa decides to lay off—we are performing microeconomic analysis.
Macroeconomics looks at the economy as a whole. Instead of focusing on one firm, it looks at "aggregates," such as national unemployment rates, total national output (GDP), or the general rate of inflation.
Exam Tip: If the subject of the sentence is a single person, a single company, or a specific product, think Micro. If the subject is "the nation," "the country," or "the general price level," think Macro.
This diagram illustrates the distinction between microeconomics, which focuses on individual agents like households and firms, and macroeconomics, which examines the economy as a whole, including aggregate outcomes such as GDP, inflation, unemployment, and interest rates. It also shows the interconnectedness of micro and macro perspectives.
Positive vs. Normative Statements
In economic discourse, it is vital to distinguish between what is and what ought to be. This is the difference between positive and normative statements.
Positive Statements
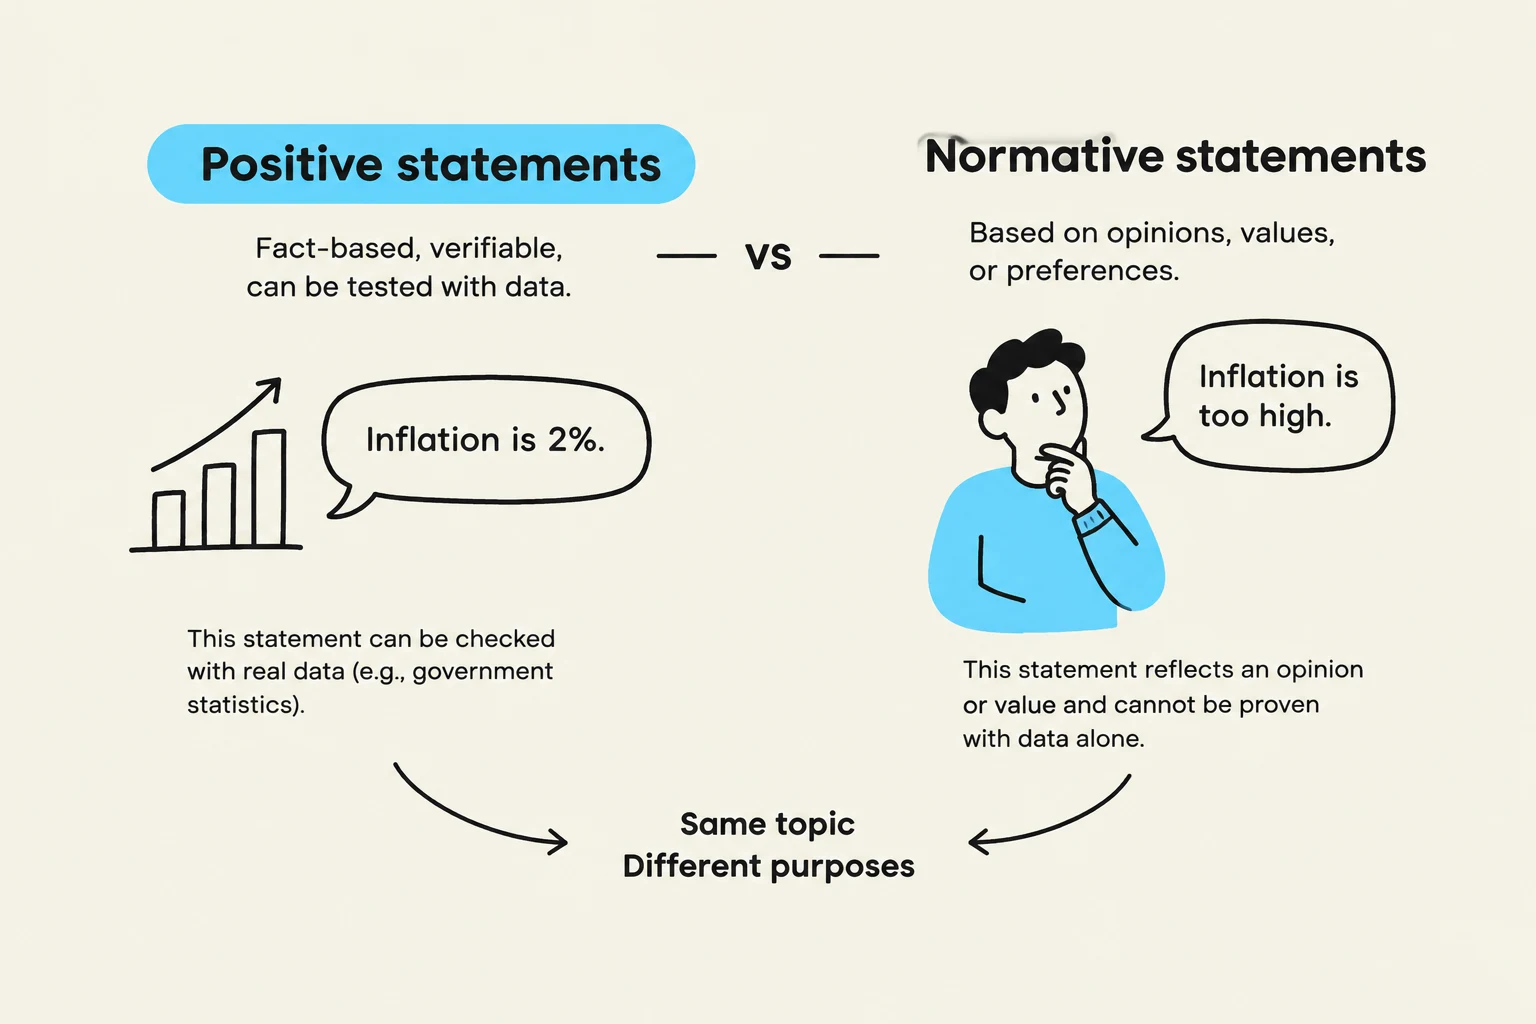
A positive statement is objective and fact-based. It describes the world as it actually exists. These statements can be tested, proven, or disproven using data and empirical evidence.
Examples from the practice set include:
"The unemployment rate in the United States was 6.8% in August 1991."
"The general price level rose by 4.4% last year."
"About 48 million people are currently estimated to be uninsured."
Note that a positive statement does not have to be correct to be positive; it simply has to be a claim about a measurable fact that can be verified.
Normative Statements
A normative statement is subjective and value-based. It expresses an opinion or a judgment about whether something is good or bad, or what should happen. These statements cannot be proven true or false by data alone because they are based on individual or societal values.
Examples from the practice set include:
"The government should provide health insurance for all."
"Inflation should be reduced by government policies."
Key Identifier: Look for the word "should". In most introductory economics courses, the presence of "should" or "ought to" is a dead giveaway for a normative statement.
This illustration contrasts positive statements, which are fact-based and verifiable, with normative statements, which are based on opinions or values, using the example of inflation.
Marginal Cost-Marginal Benefit Analysis
One of the most powerful tools in applied microeconomics is marginal analysis. This involves comparing the additional benefit of an action to the additional cost of that same action.
The Logic of Optimization
Economists argue that rational actors will continue an activity as long as the Marginal Benefit (MB) is greater than or equal to the Marginal Cost (MC). The optimal level of an activity is reached at the exact point where:
MB = MC
\end{aligned}$$
If $MB > MC$, you should do more of the activity because you are gaining more than you are spending. If $MC > MB$, you have gone too far and should do less of the activity because the last unit cost you more than it was worth.
### Application: The Pollution Problem
A classic application of this is the question: *"Should we eliminate all pollution in the world?"*.
From a marginal analysis perspective, the answer is almost always **no**. As we attempt to eliminate the very last traces of pollution, the Marginal Cost ($MC$) of doing so rises exponentially (requiring incredibly expensive technology or complete cessation of industrial activity), while the Marginal Benefit ($MB$) of removing that tiny, final amount of pollution becomes extremely small.
To find the socially optimal level of pollution, we look for the point where the cost of reducing one more unit of pollution is exactly equal to the benefit gained from that reduction.

By understanding these three pillars—the scale of analysis (Micro vs. Macro), the nature of the claim (Positive vs. Normative), and the logic of decision-making (Marginal Analysis)—you can navigate almost any introductory economic problem.
$$$
$$$
Keep reading for free.
Create an account to finish this reading and make it part of your study routine.