Navigating the complexities of international trade requires a dual understanding of how to sell products effectively (marketing) and how to navigate the regulatory and political landscapes of foreign nations. For a business to successfully expand globally, it must align its internal capabilities with the external realities of target markets, ranging from distribution logistics to the impact of government-imposed tariffs and regional trade agreements.
Generic Marketing Strategies for Exporting
When entering a foreign market, companies often utilize the "4Ps" of the marketing mix: Product, Price, Promotion, and Place. To gain a competitive edge, exporters must develop specific strategies within these categories:
Product Strategies: Companies often succeed by offering products with unique features not available in the local market. These features might relate to materials, style, functionality, or even the prestige of the country of origin.
Pricing Strategies: Some firms leverage a cost advantage through proprietary production methods, unique technologies, or economies of scale. This allows them to use price as a primary basis of competition.
Target Market Selection: A market is only considered attractive if it meets three criteria simultaneously: Opportunity (demand and growth), Accessibility (logistics and low trade barriers), and Fit (the company's resources and risk tolerance).
Exam Tip: When assessing a target market, remember that "Accessibility" is often hindered by import duties, quotas, bans, and special labeling or health regulations.
Distribution Methods and Tactics
Choosing how to get a product to a foreign consumer is a critical decision that affects both cost and control. Companies can choose between various levels of involvement, ranging from indirect exporting to full acquisition.
Intermediaries: Agents vs. Distributors
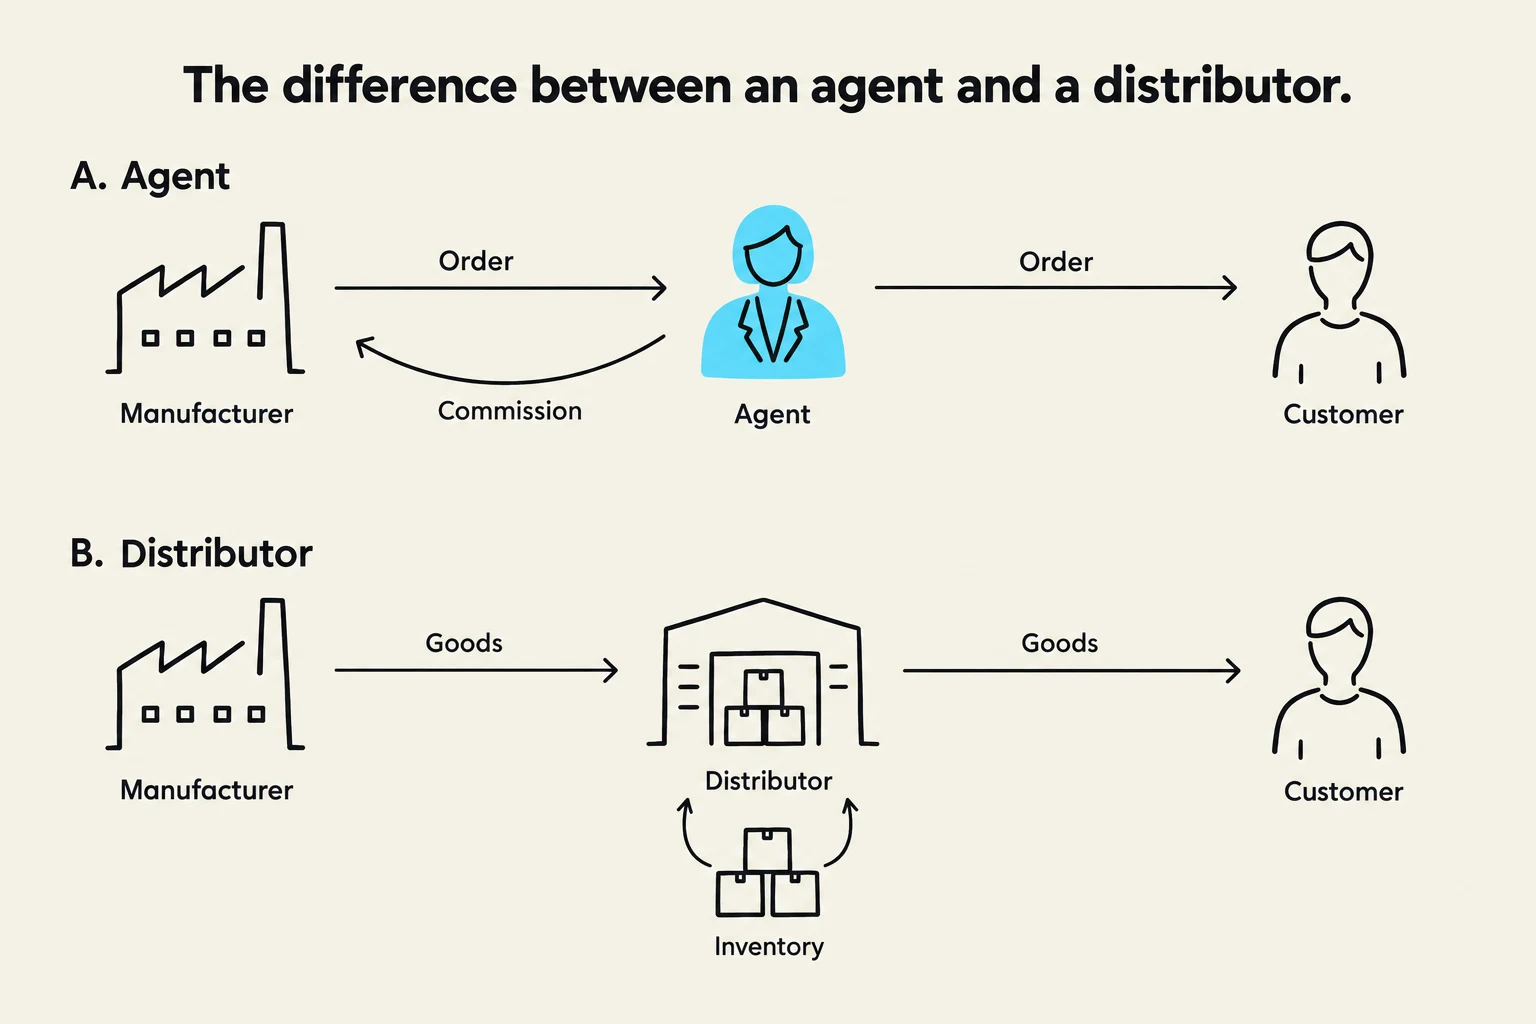
This diagram illustrates the difference between an agent and a distributor in a supply chain. An agent acts as an intermediary, facilitating orders between a manufacturer and a customer, and receives a commission. A distributor purchases goods from a manufacturer, holds them in inventory, and then sells them to customers.
Many exporters rely on local intermediaries to bridge the gap between their home base and the foreign consumer.
Foreign Sales Representatives (Agents): These are individuals or entities residing in the foreign country who act as salespeople for the manufacturer. They typically secure orders in exchange for a commission.
Distributors: Unlike agents, a distributor is a firm that buys and resells the goods. They usually maintain an inventory of the manufacturer's products and may act on an exclusive basis for a specific territory.
Using intermediaries provides benefits such as local market intelligence and customer access, but it carries risks like loss of brand control or inconsistent service.
Managing Risk with Incoterms®
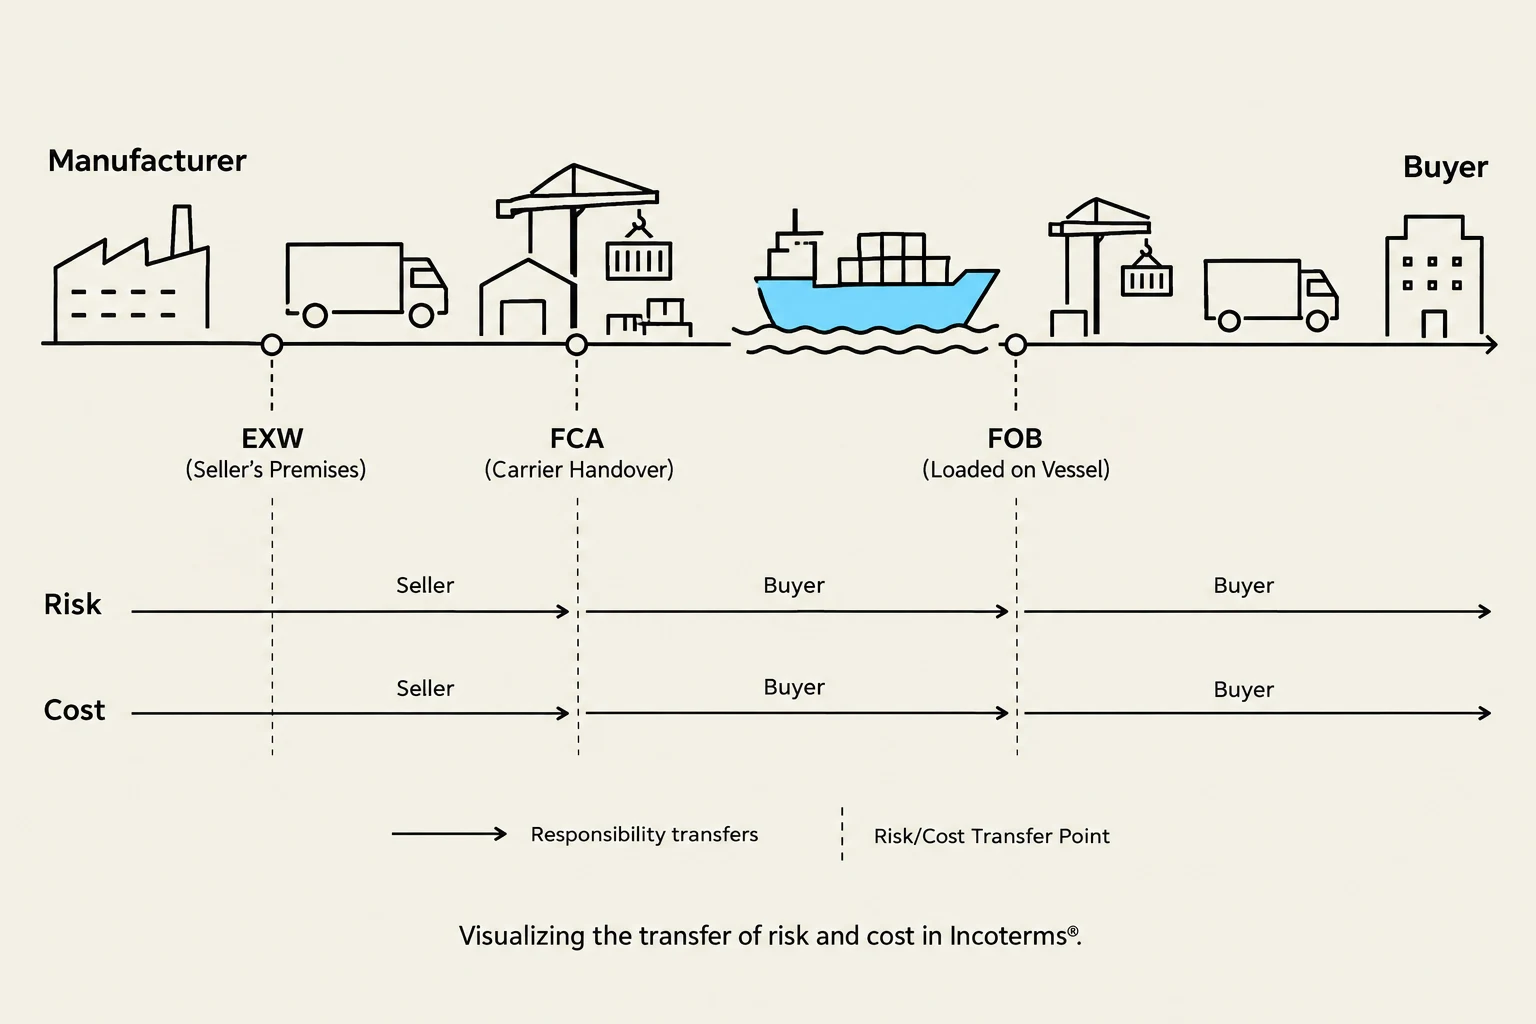
This diagram illustrates the transfer of risk and cost between a seller and buyer at different Incoterms® points, such as EXW, FCA, and FOB.
To mitigate the risks associated with shipping and delivery, exporters use Incoterms® (International Commercial Terms). These rules define exactly where the costs and risks transfer from the seller to the buyer. Before choosing a term, exporters must consider the mode of transport, the specific delivery place, who clears customs, and exactly when the risk of loss shifts to the buyer.
Common groupings include:
EXW (Ex Works): The seller's only responsibility is to make the goods available at their own premises.
FCA (Free Carrier): The seller delivers the goods to a named carrier.
FOB (Free On Board): Specifically for sea or inland waterway transport; the seller loads the goods on board the vessel.
Trade Barriers: Tariffs, Quotas, and Sanctions
Governments often intervene in trade to protect domestic industries or achieve political objectives.
Tariffs and Quotas
A tariff is a tax or duty imposed by a government to raise the price of imported products. This is often done to ensure domestic companies can continue to supply essential materials (such as for national defense) or to support key local industries. Import quotas are another tool used to restrict the quantity of goods entering a country.
Economic Sanctions
Sanctions are more severe tools used to restrict or prohibit transactions with specific entities or nations. These can be:
Country-based: Restricting all transactions involving a specific country.
List-based: Prohibiting transactions with specific individuals or companies.
Sanctions can have devastating effects, such as blocking access to international payment systems (like Visa or Mastercard) or restricting access to U.S. dollars.
Regional Trade Agreements (RTAs)
To facilitate easier commerce, many nations enter into Regional Trade Agreements (RTAs), such as CUSMA, the EU Common Market, or CETA. While these agreements generally promote trade, they result in two distinct economic phenomena:
Trade Creation: This occurs when a member country starts importing a product from another member country that it previously produced itself.
Trade Diversion: This occurs when a member country stops importing from a low-cost non-member and instead imports from a higher-cost member simply because the member enjoys lower tariff rates under the agreement.
Critical Concept: A regional trade agreement may have a net negative effect on its members if the level of trade diversion is greater than the level of trade creation.
Rules of Origin
Following events like Brexit, "Rules of Origin" become vital. When trade blocs change, companies must prove where a product was actually made to determine which tariff rates apply. For example, when the UK left the EU, Northern Ireland and the Republic of Ireland ended up under different tariff regimes.
Game Theory in International Trade
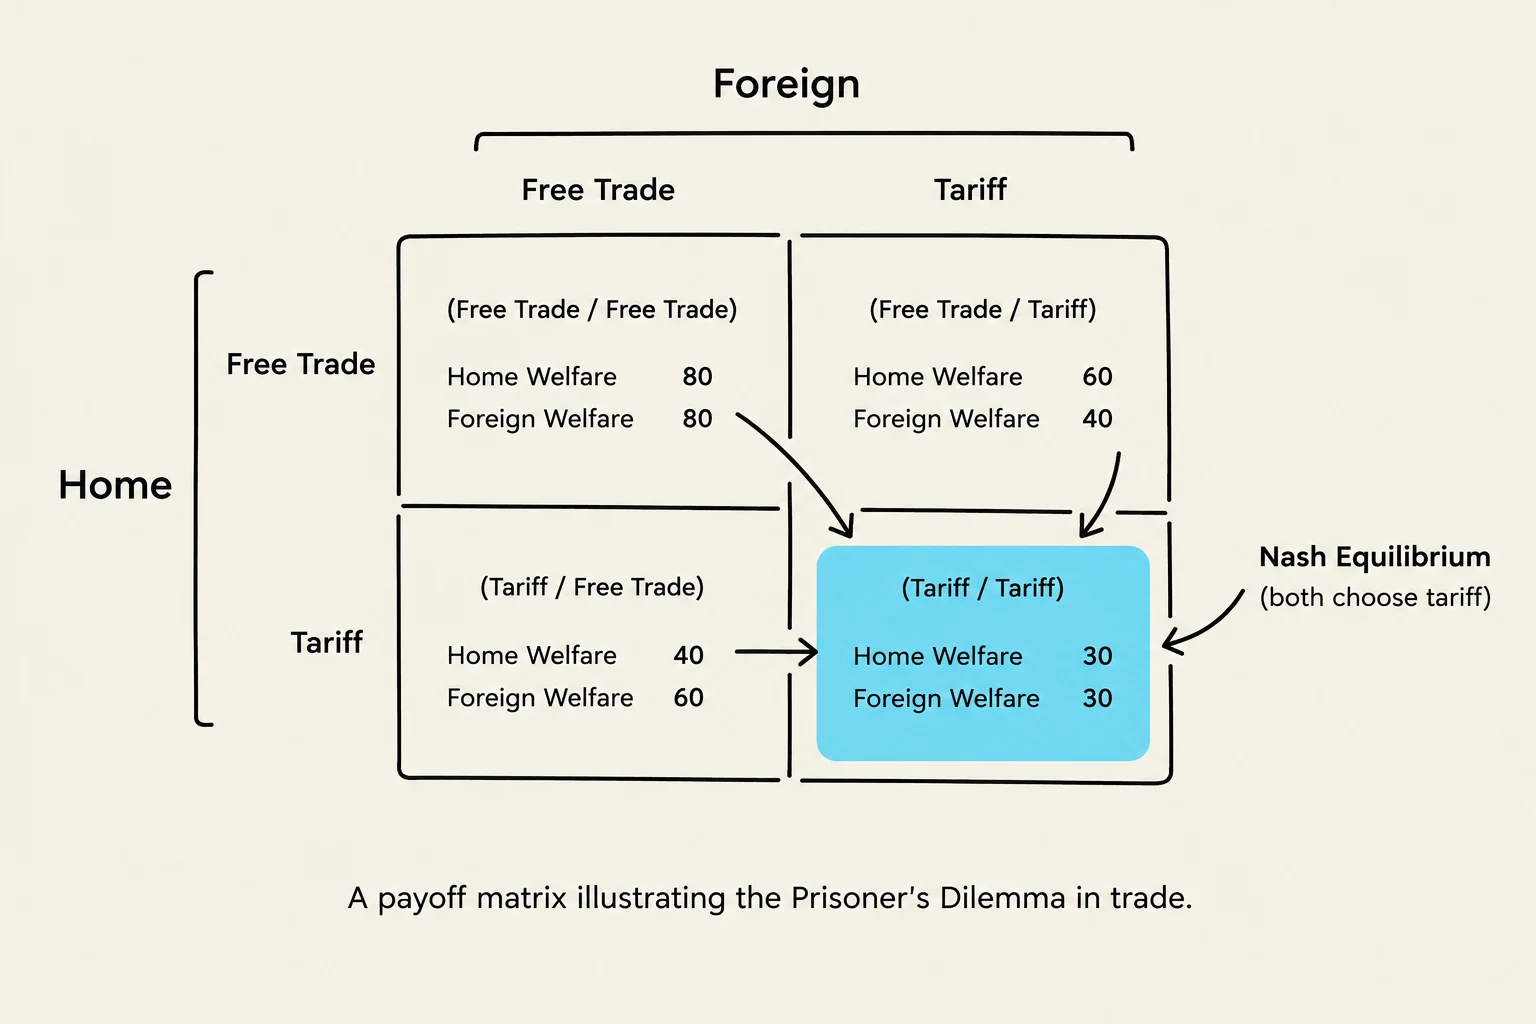
A payoff matrix illustrating the Prisoner's Dilemma in trade.
The decision to impose tariffs can be analyzed using a Payoff Matrix, which illustrates the welfare of "Home" and "Foreign" countries based on their choices.
In many trade disputes, countries fall into a pattern similar to the "Prisoner's Dilemma." Even though both countries would be better off with free trade (the upper-left quadrant of a matrix), they often end up in a Nash Equilibrium where both countries apply tariffs (the lower-right quadrant). This happens because, given that the other country is likely to impose a tariff, the "best" individual response for each country is to also impose a tariff, even though the resulting outcome is undesirable for both.
Keep reading for free.
Create an account to finish this reading and make it part of your study routine.