International Capital Structure: MNCs vs. Domestic Firms
This article compares the capital structure decisions of multinational corporations (MNCs) with those of domestic firms, highlighting the complexities introduced by multiple currencies, tax jurisdictions, and geopolitical risks in international finance.
When a company decides how to finance its operations, it faces a fundamental question: should it use its own equity or borrow money (debt)? This decision is known as capital structure. For a domestic firm operating within a single country, this decision is primarily driven by local tax laws, the cost of local debt, and the risk profile of its domestic cash flows. However, for a Multinational Corporation (MNC), the complexity increases exponentially. An MNC must navigate multiple currencies, varying tax jurisdictions, geopolitical risks, and international capital markets.
This article explores the nuances of international capital structure, comparing the strategic considerations of MNCs against their domestic counterparts to understand why the "optimal" mix of debt and equity differs across borders.
The Foundation: Domestic Capital Structure
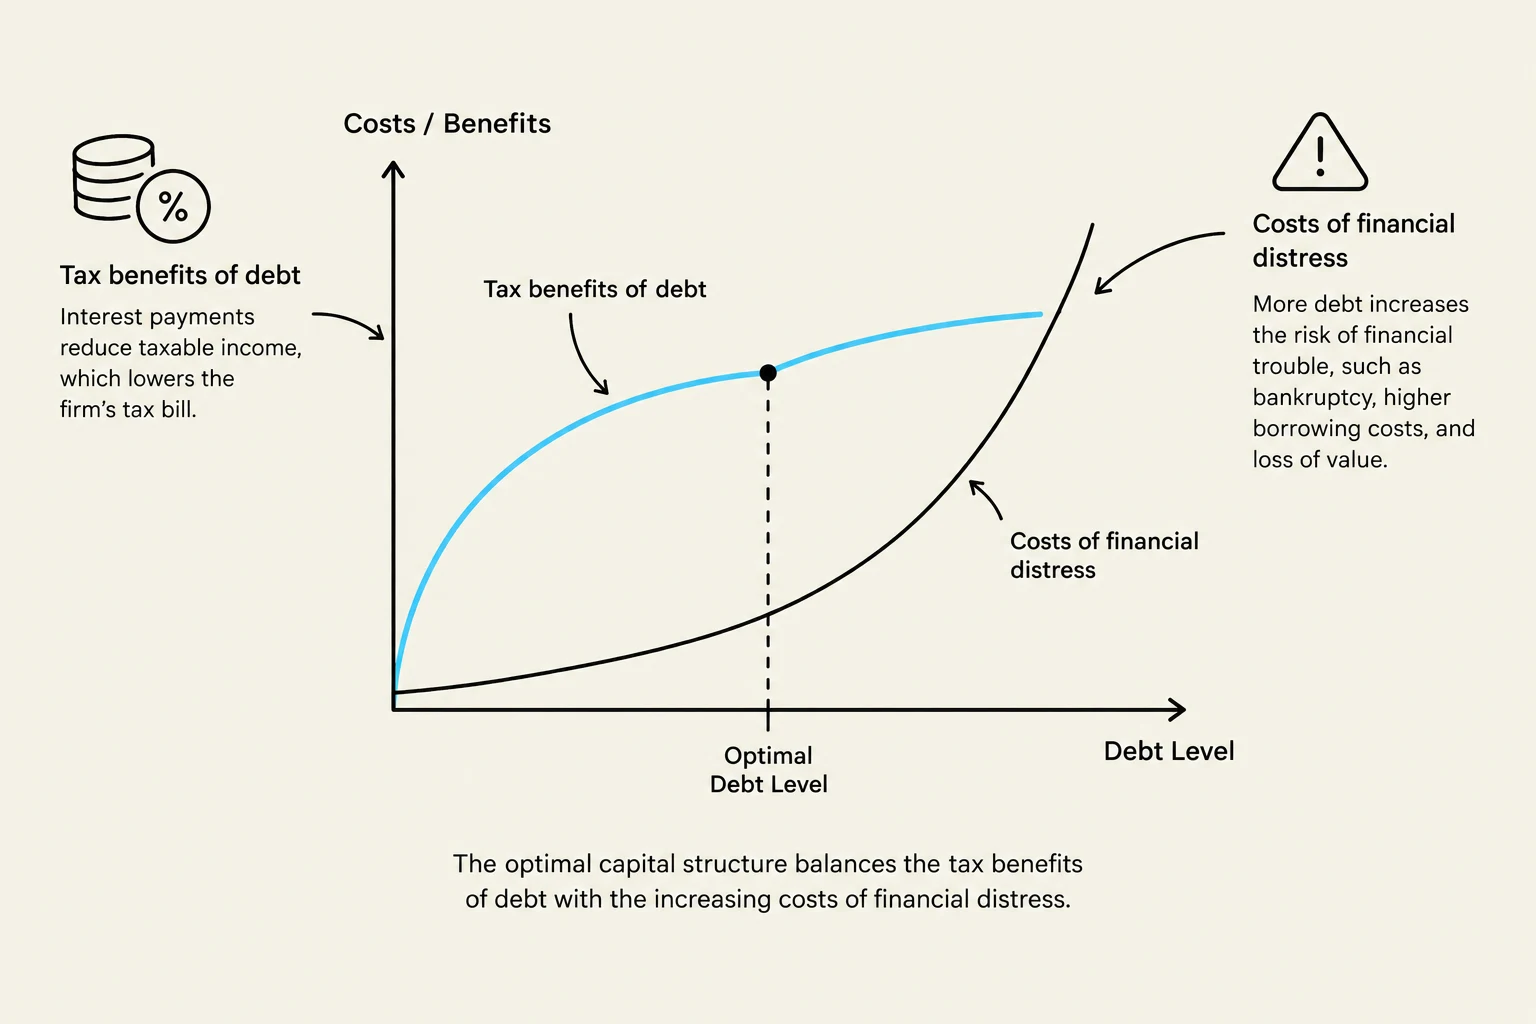
To understand the international context, we must first establish the baseline of domestic capital structure. Most domestic firms follow the principles of the Trade-off Theory. This theory suggests that a firm seeks to balance the tax benefits of debt (the interest tax shield) against the costs of potential financial distress and bankruptcy.
In a domestic setting, the firm's primary goal is to minimize its Weighted Average Cost of Capital (WACC). The formula for WACC is:
WACC=we⋅re+wd⋅rd⋅(1−T)
Where:
we is the proportion of equity.
re is the cost of equity.
wd is the proportion of debt.
rd is the cost of debt.
T is the corporate tax rate.
For a domestic firm, T is a single, predictable value, and the cash flows used to service debt are generally in the same currency as the debt itself, reducing exchange rate risk.
This graph illustrates the trade-off between the tax benefits of debt and the costs of financial distress in determining an optimal capital structure.
Exam Tip: When calculating WACC for a domestic firm, always remember to multiply the cost of debt by (1−T) to account for the tax deductibility of interest payments.
How MNCs Differ: The International Complexity
Multinational Corporations do not simply apply domestic logic to foreign subsidiaries. Instead, they manage a global portfolio of assets and liabilities. Several key factors differentiate the MNC's approach from that of a domestic firm.
1. Diversification of Cash Flows
One of the greatest advantages of an MNC is geographic diversification. While a domestic firm is highly sensitive to the economic cycle of its home country, an MNC earns revenues in multiple economies. If the US economy enters a recession, the MNC's European or Asian subsidiaries might still be performing well.
This diversification of cash flows can actually allow an MNC to carry a higher level of debt than a domestic firm with similar total assets. Because the aggregate cash flow is less volatile due to non-correlated international markets, the probability of a total firm-wide default is reduced.
2. Tax Arbitrage and Transfer Pricing
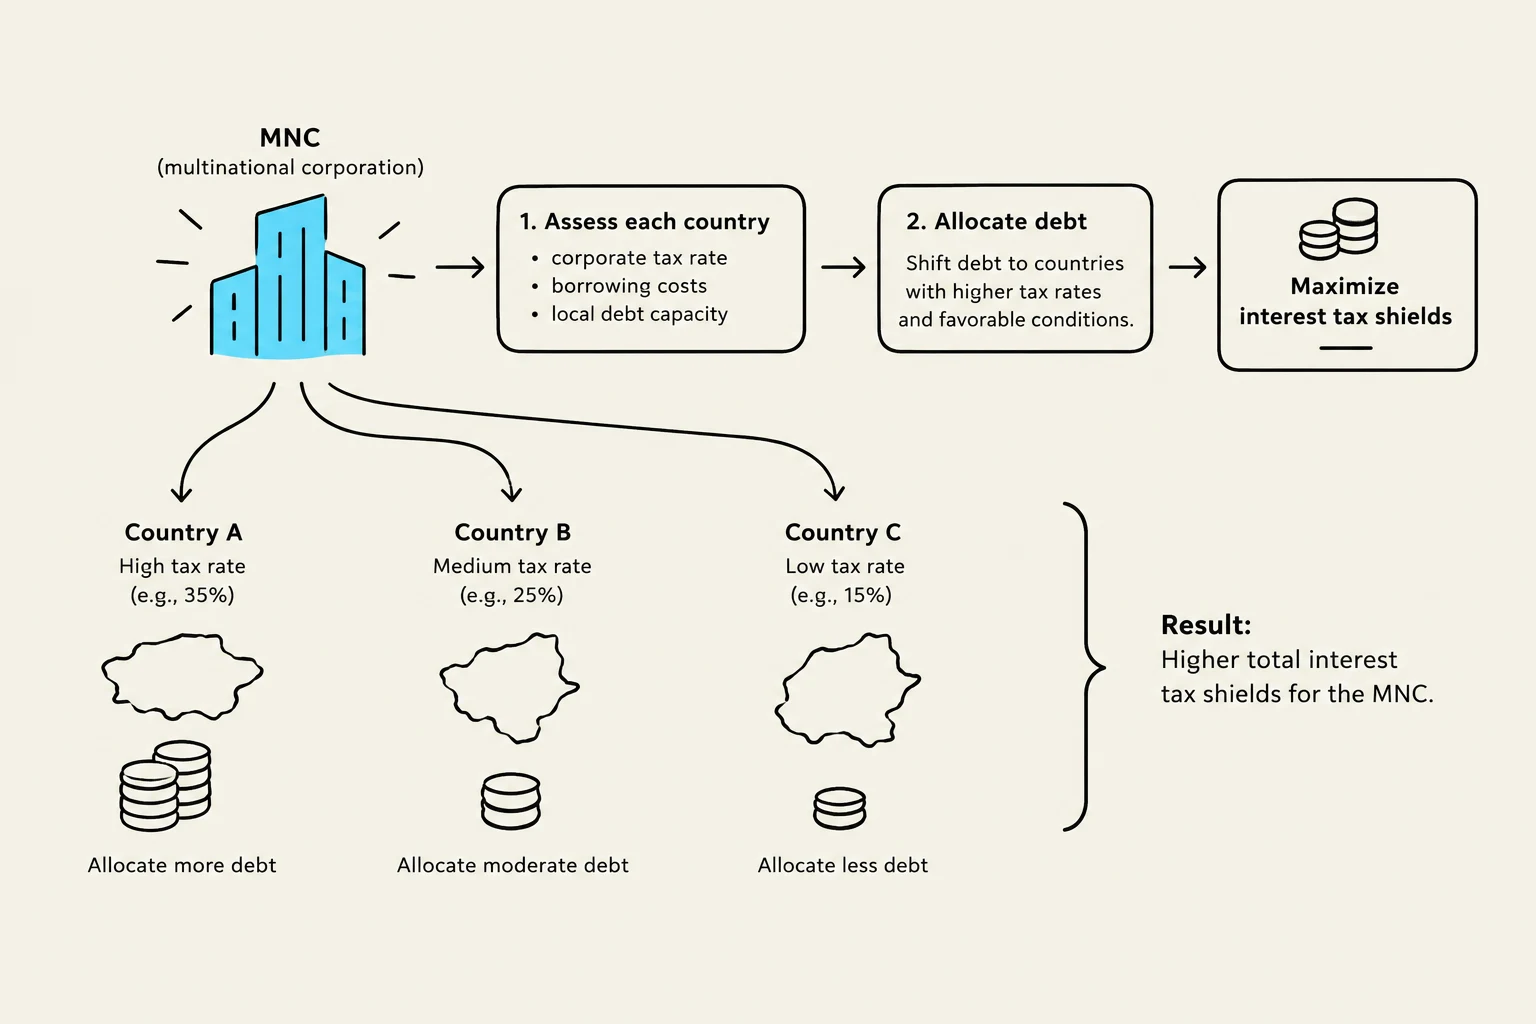
While a domestic firm deals with one tax code, an MNC deals with many. This creates opportunities for "tax arbitrage." An MNC can optimize its capital structure by issuing debt in high-tax jurisdictions to maximize the interest tax shield, while keeping equity in lower-tax jurisdictions.
This diagram illustrates how a multinational corporation (MNC) can strategically allocate debt across different countries to maximize interest tax shields. The process involves assessing each country based on factors like corporate tax rate, borrowing costs, and local debt capacity. The MNC then shifts debt to countries with higher tax rates and favorable conditions, leading to higher total interest tax shields.
3. Exchange Rate Risk and Currency Matching
For a domestic firm, currency risk is virtually non-existent in its capital structure. For an MNC, it is a central concern. If an MNC borrows in Japanese Yen (JPY) to fund a project in Brazil (BRL), it faces significant exchange rate risk. If the Yen appreciates against the Real, the cost of servicing that debt in local terms could skyrocket.
To mitigate this, MNCs often use a strategy called matching. This involves matching the currency of the debt with the currency of the cash flows generated by the specific subsidiary.
Comparing the Optimal Structure
The "optimal" capital structure is the mix of debt and equity that maximizes the firm's value. Because of the factors mentioned above, the optimal point for an MNC often shifts compared to a domestic firm.
Feature
Domestic Firm
Multinational Corporation (MNC)
Primary Risk
Business & Financial Risk
Business, Financial, & Exchange Rate Risk
Cash Flow Volatility
Higher (Single economy)
Lower (Diversified economies)
Tax Shield Opportunity
Limited to one jurisdiction
High (Can optimize across borders)
Debt Capacity
Constrained by local economic cycles
Potentially higher due to diversification
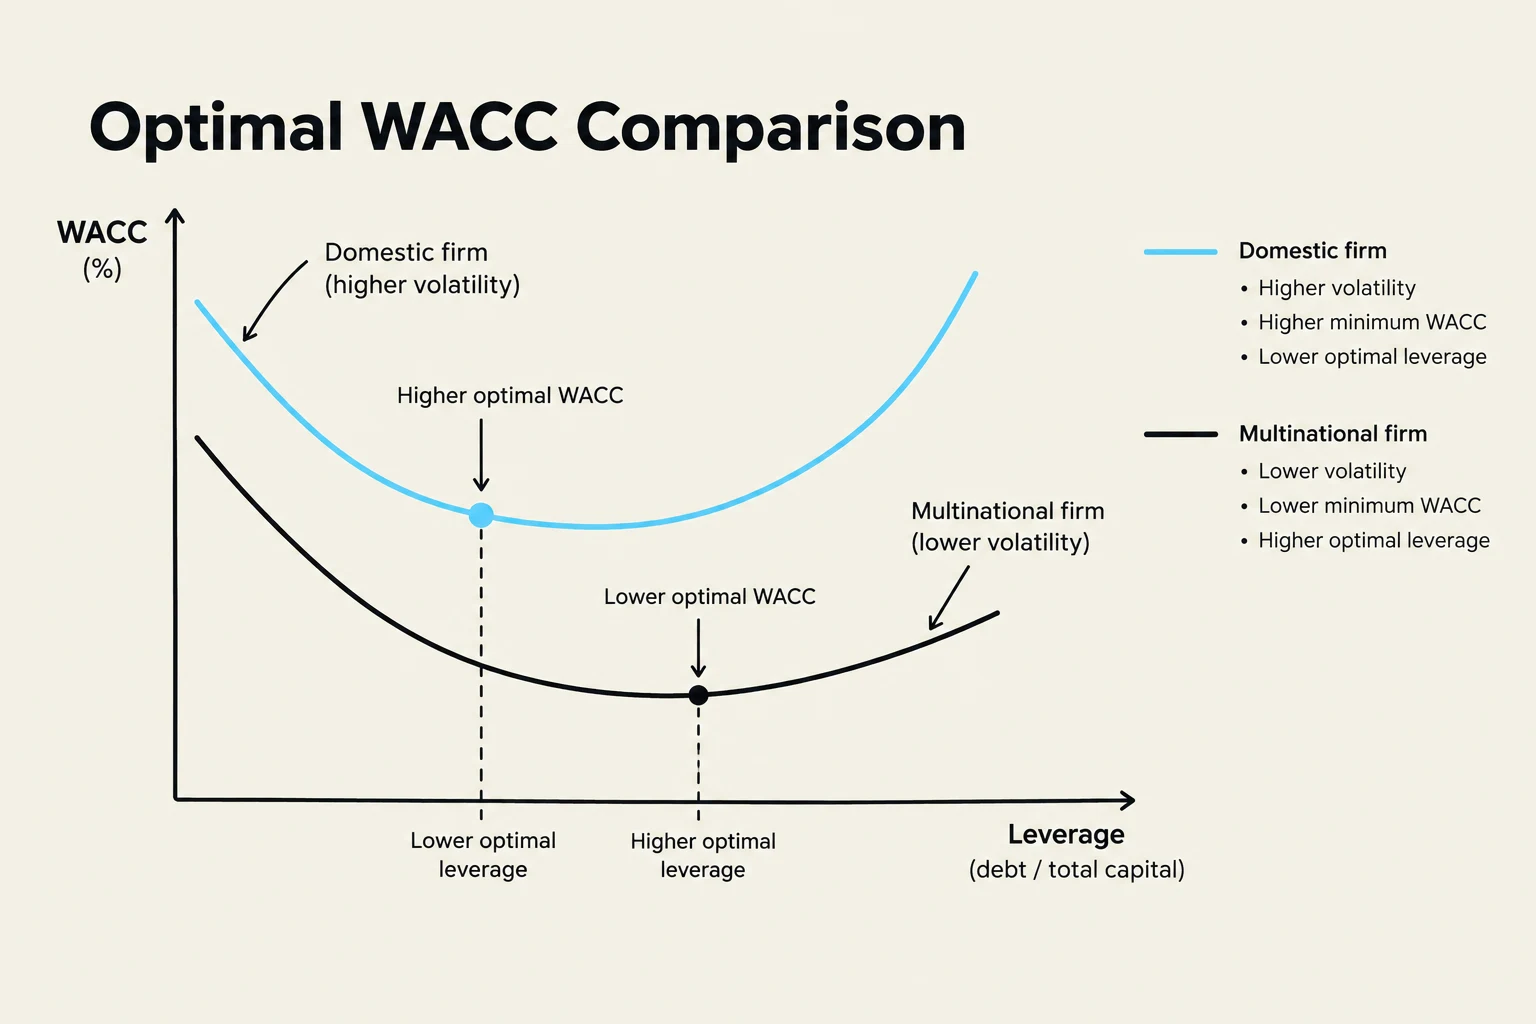
This graph compares the Weighted Average Cost of Capital (WACC) for a domestic firm and a multinational firm as leverage changes. It illustrates that a domestic firm with higher volatility has a higher optimal WACC and lower optimal leverage compared to a multinational firm with lower volatility, which has a lower optimal WACC and higher optimal leverage.
Summary of Key Differences
In summary, while both domestic and international firms aim to minimize their WACC and balance tax benefits against distress costs, the MNC has a much broader toolkit and a more complex set of risks.
Diversification: MNCs can often leverage more debt because their global revenue streams are more stable than a single-country firm.
Taxation: MNCs can strategically place debt to exploit global tax differences.
Currency: MNCs must carefully manage the relationship between the currency of their debt and the currency of their earnings to avoid insolvency caused by exchange rate fluctuations.
Understanding these nuances is essential for any student of international finance, as the globalized nature of modern business means that the "domestic" model is increasingly becoming the exception rather than the rule.
Keep reading for free.
Create an account to finish this reading and make it part of your study routine.