Global Cash Flow Forecasting: Managing Currency Volatility and Repatriation
This content explains global cash flow forecasting for multinational corporations, focusing on managing currency volatility through exchange rate expectations and accounting for repatriation restrictions like taxes and capital controls. It outlines a four-step process for creating robust long-term financial models.
For a multinational corporation (MNC), managing cash is significantly more complex than it is for a domestic firm. While a domestic company focuses on timing inflows and outflows within a single currency, an MNC must account for the fact that its cash is often "trapped" in different denominations and subject to the whims of international markets. Global cash flow forecasting is the process of projecting these multi-currency flows while accounting for two critical variables: exchange rate fluctuations and legal or regulatory restrictions on moving money across borders.
The Challenge of Currency Volatility
When forecasting long-term cash flows, an MNC cannot simply assume that the exchange rate observed today will remain constant throughout the projection period. Because most long-term projects or operational cycles span months or years, the "functional currency" of a subsidiary might generate significant cash, but the value of that cash in the parent company's reporting currency can swing wildly due to market movements.
To build a robust forecast, treasury managers must incorporate exchange rate expectations. This often involves using forward rates—the rates at which a currency can be exchanged for another at a specific future date—rather than current spot rates.
Exam Tip: When calculating the future value of foreign cash flows in a reporting currency, always distinguish between the transaction exposure (the risk that the exchange rate will change before a specific transaction is settled) and the translation exposure (the risk that the value of foreign assets/cash will change when consolidated into the parent's financial statements).
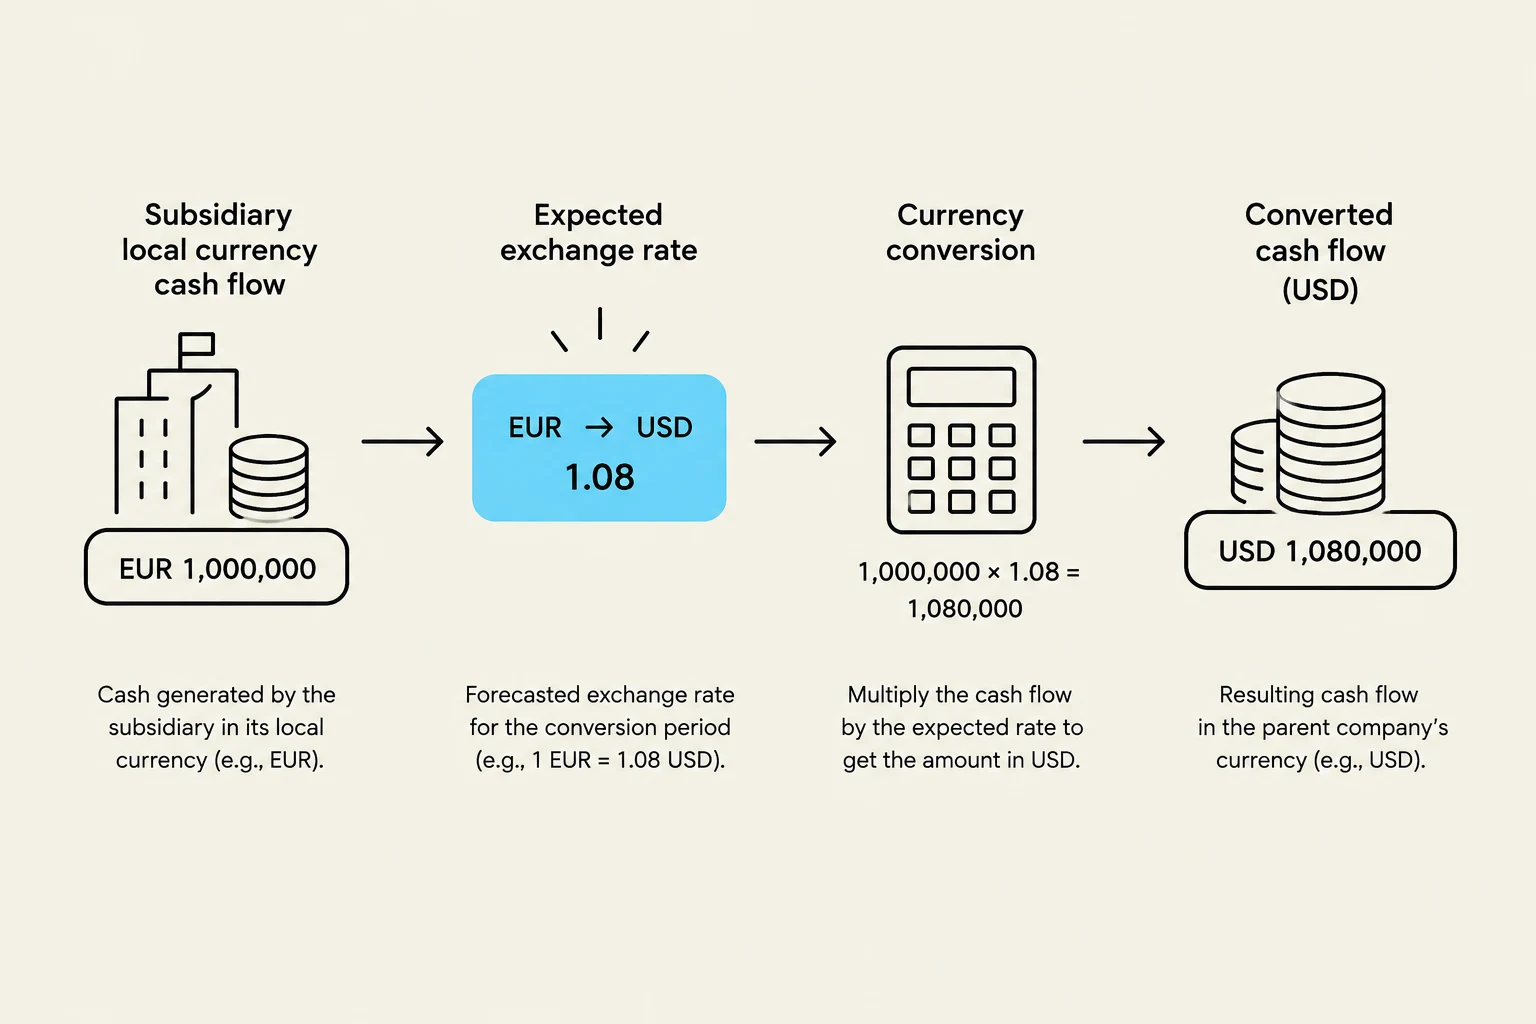
This diagram illustrates the process of converting local currency cash flow from a subsidiary to the parent company's currency, using an expected exchange rate and a calculator for the conversion.
If a company expects to receive $1,000,000$ units of a foreign currency in twelve months, and the current spot rate is 1.20 per unit, the current value is $1,200,000$ in the home currency. However, if the forward rate is 1.10, the forecasted value must be adjusted:
Even if a subsidiary is highly profitable and generates massive cash inflows, that cash is not "available" to the parent company until it is repatriated. Repatriation refers to the process of transferring funds from a foreign subsidiary back to the parent company.
In many emerging markets, governments impose strict controls to prevent capital flight and maintain stability in their own local currency. These restrictions can take several forms:
Taxation: High withholding taxes on dividends or interest payments sent abroad.
Capital Controls: Legal limits on the total amount of currency that can be moved out of a country in a given period.
Conversion Requirements: Mandates that foreign companies must convert local currency into the local legal tender before it can be exported, often at unfavorable official rates.
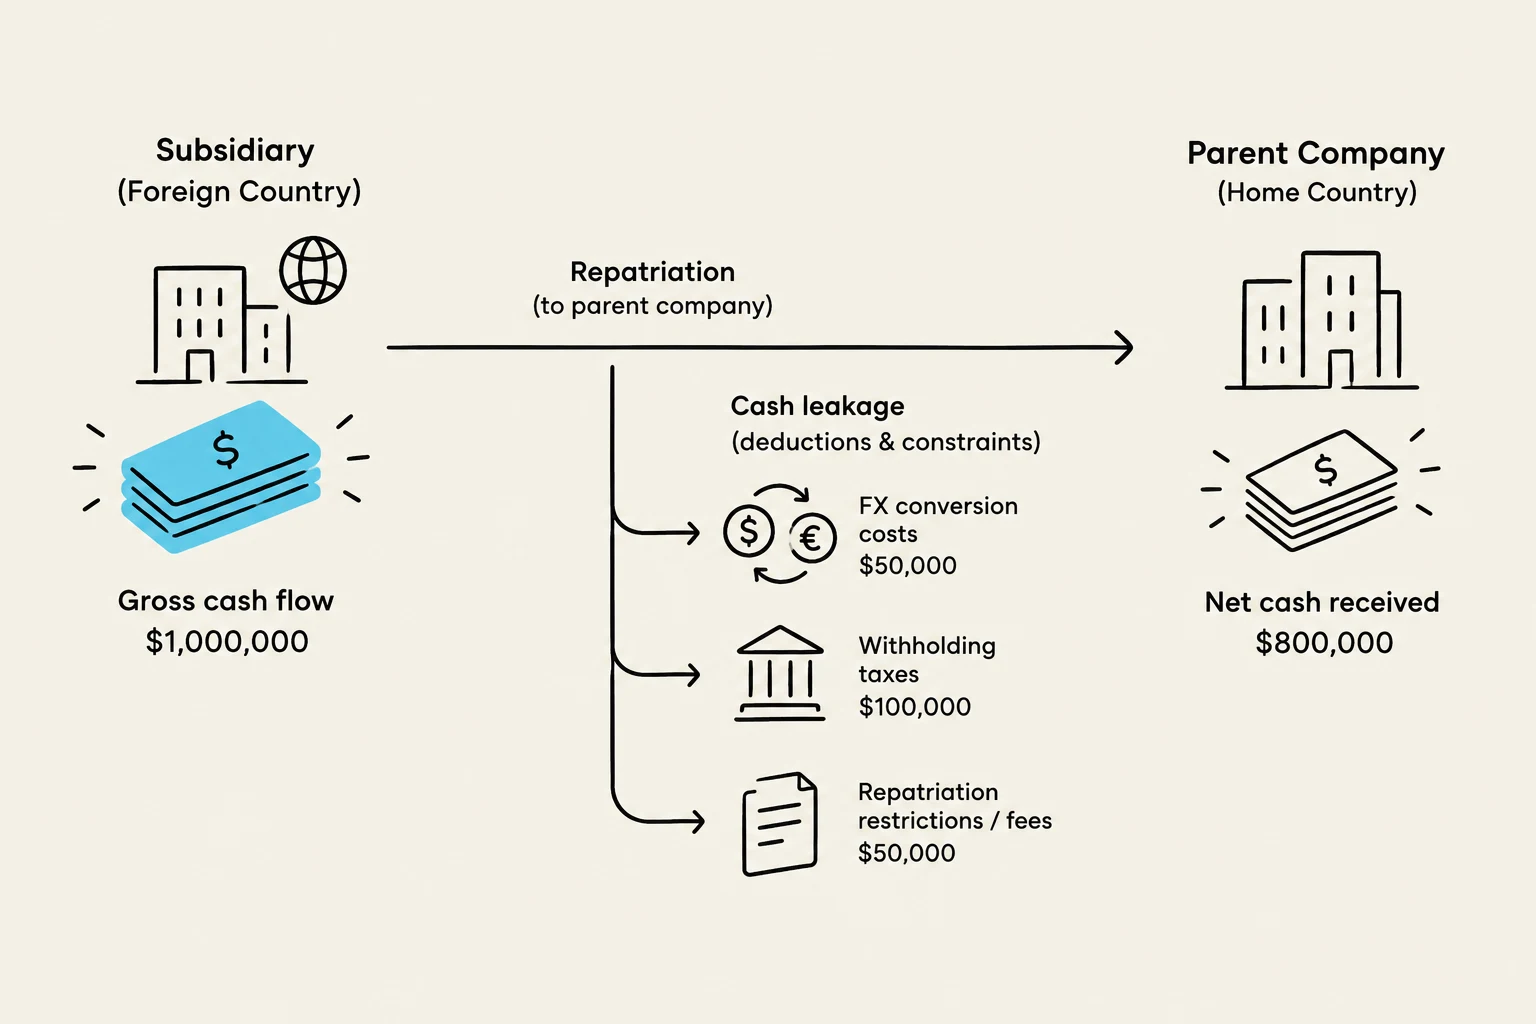
When building a long-term projection, a treasurer must apply a "haircut" or a discount to the projected cash flows of subsidiaries in restrictive jurisdictions. If a subsidiary projects a cash flow of C, but the government imposes a $20%$ withholding tax on all repatriated dividends, the effective cash flow available to the parent is:
Available Cash Flow=C⋅(1−Tax Rate)
This diagram illustrates the process of repatriation of funds from a subsidiary in a foreign country to its parent company, detailing various cash leakages such as FX conversion costs, withholding taxes, and repatriation restrictions/fees, ultimately showing the net cash received.
Integrating Volatility and Restrictions into Projections
A sophisticated global cash flow model does not just provide a single number; it provides a range of possibilities. This is often achieved through scenario analysis or Monte Carlo simulations, where different exchange rate paths and different levels of regulatory tightening are tested.
To create a coherent long-term model, the following steps are typically taken:
Local Currency Projection: Forecast all inflows and outflows in the local currency of each subsidiary.
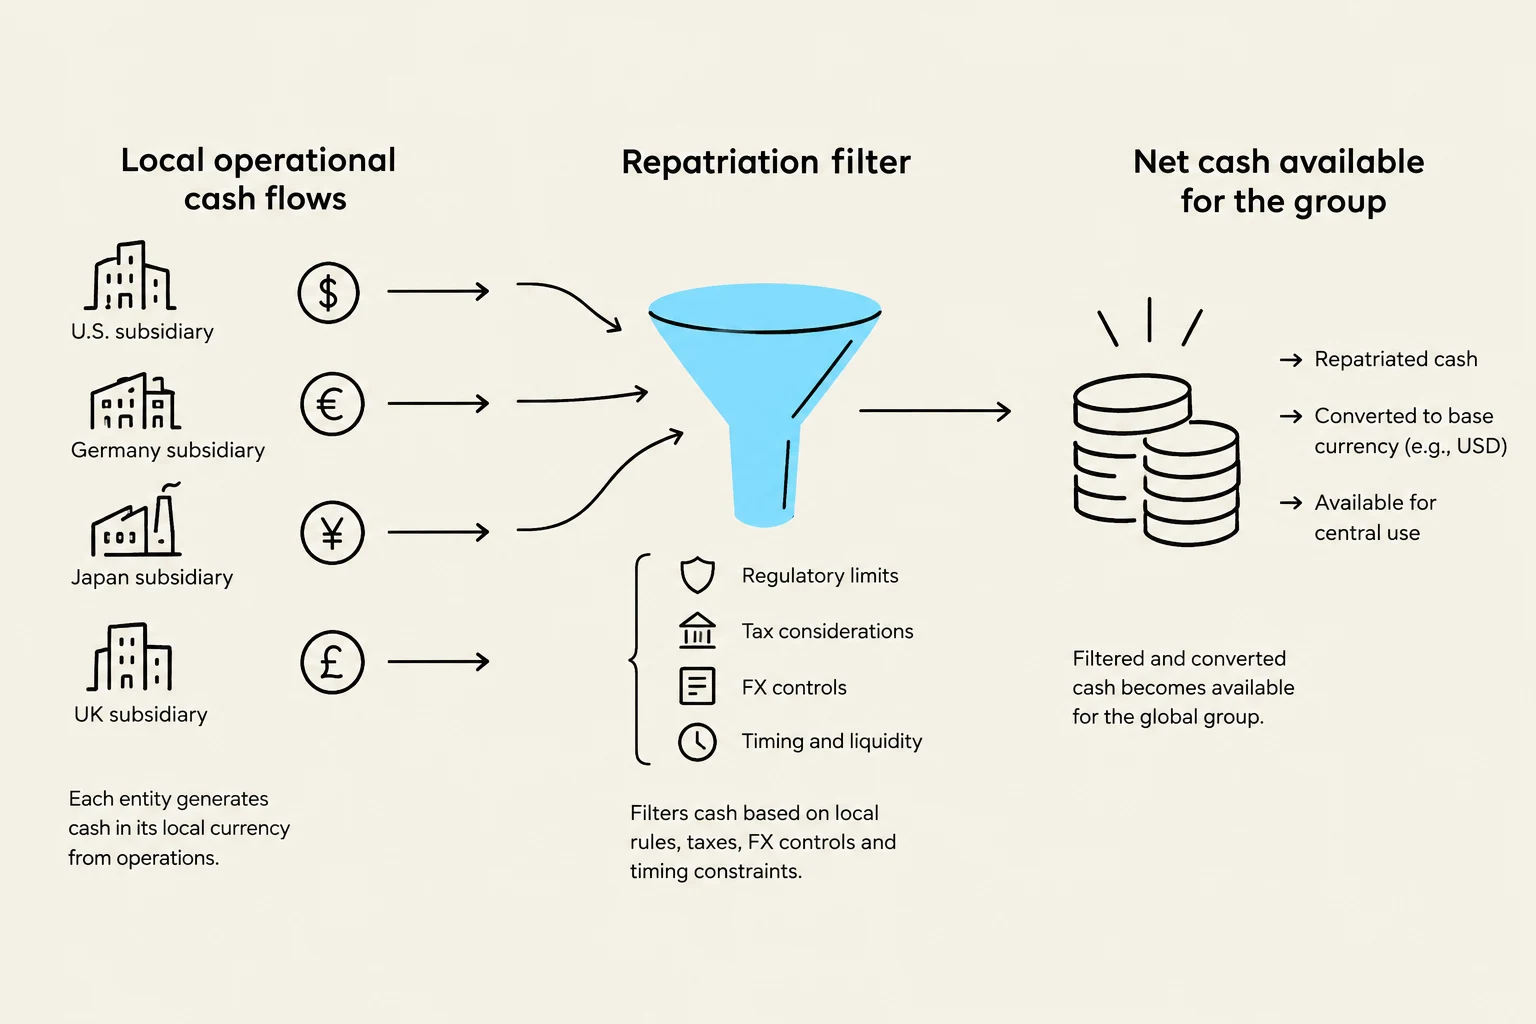
Apply Repatriation Filters: Subtract expected taxes, transfer costs, and account for any volume limits imposed by local regulations.
Currency Conversion: Convert the "net repatriatable" amount into the parent's reporting currency using forecasted exchange rates (e.g., forward rates or inflation-adjusted spot rates).
Aggregation: Sum the converted flows from all global subsidiaries to determine the total projected liquidity available to the parent company.
This diagram illustrates the process of local operational cash flows from different subsidiaries being filtered through a repatriation filter, considering regulatory limits, tax considerations, FX controls, and timing/liquidity, to result in net cash available for the group, which is repatriated, converted to a base currency, and available for central use.
By accounting for these two dimensions—the market value of the money (currency) and the legal ability to move the money (repatriation)—multinational firms can avoid the trap of "paper profits," where a company appears wealthy on a consolidated balance sheet but lacks the actual liquidity to fund global operations or pay dividends.
Keep reading for free.
Create an account to finish this reading and make it part of your study routine.